One API. Full Infrastructure.
Designed for compliance
from day one
One modular platform – delivered through a plug and play API integration.
Request a partner briefing A connected institutional stack.
Stablecoin payments, custody, brokerage, tokenization and yield.
Begin with a commercially relevant settlement use case, then expand into the rest of the digital-asset operating stack as product scope, jurisdiction and market conditions allow.
Everything your customers need, under your brand, inside your app. CuduEx builds the digital-asset infrastructure and will run it once authorised; you keep the customer, the brand and the KYC.
Every capability is built to institutional standard - designed to be regulated, auditable, and to operate inside the risk and compliance framework you already run. Not adapted to it. Built for it.
Stablecoin payments
Cross-border payments for your corporate customers, designed to settle on fiat-referenced stablecoin rails with local currency at both ends.
- Designed for settlement in minutes, not days
- Trade-documented corridors
- Built so originator and beneficiary information travels with every transfer
- Full settlement audit trail
Institutional custody
Safekeeping for digital assets, designed to regulated standards and held to the same rigour your auditor already applies to securities.
- MPC-secured vaults with multi-party approval
- Multi-signature governance
- Segregated client accounts, never pooled with our own assets
Brokerage / On-Off Ramp
Convert between local currency and digital assets at the point a transaction begins and ends, and handle larger orders on a quoted basis.
- Local currency to digital asset, and back
- Request-for-quote handling for size, designed to minimise market impact
- Pricing from multiple liquidity sources
- Post-trade reporting and audit trail
Tokenization
A structured workflow for eligible real-world asset programmes, subject to jurisdiction and legal requirements.
Yield
A disclosure-led allocation and redemption journey for approved yield products.
- Staking on supported networks
- Treasury yield on institutional balances
- Daily accrual and reporting
- No lending of client assets, no rehypothecation
Built around the partner institution.
- 01
Sender institution
Initiates the branded customer journey.
- 02
CuduEx API
Configured controls and review steps.
- 03
Stablecoin rail
Settlement leg across the corridor.
- 04
CuduEx API
Settlement and payout orchestration.
- 05
Recipient institution
Delivers the local payout experience.
Partner ownership stays intact: the institution retains its brand, customer relationship and KYC while CuduEx supports the underlying digital-asset service rails.
A B2B trade payment, in the partner's own portal.
How a cross-border supplier payment could look to a partner institution's corporate customer, carrying the partner's brand.
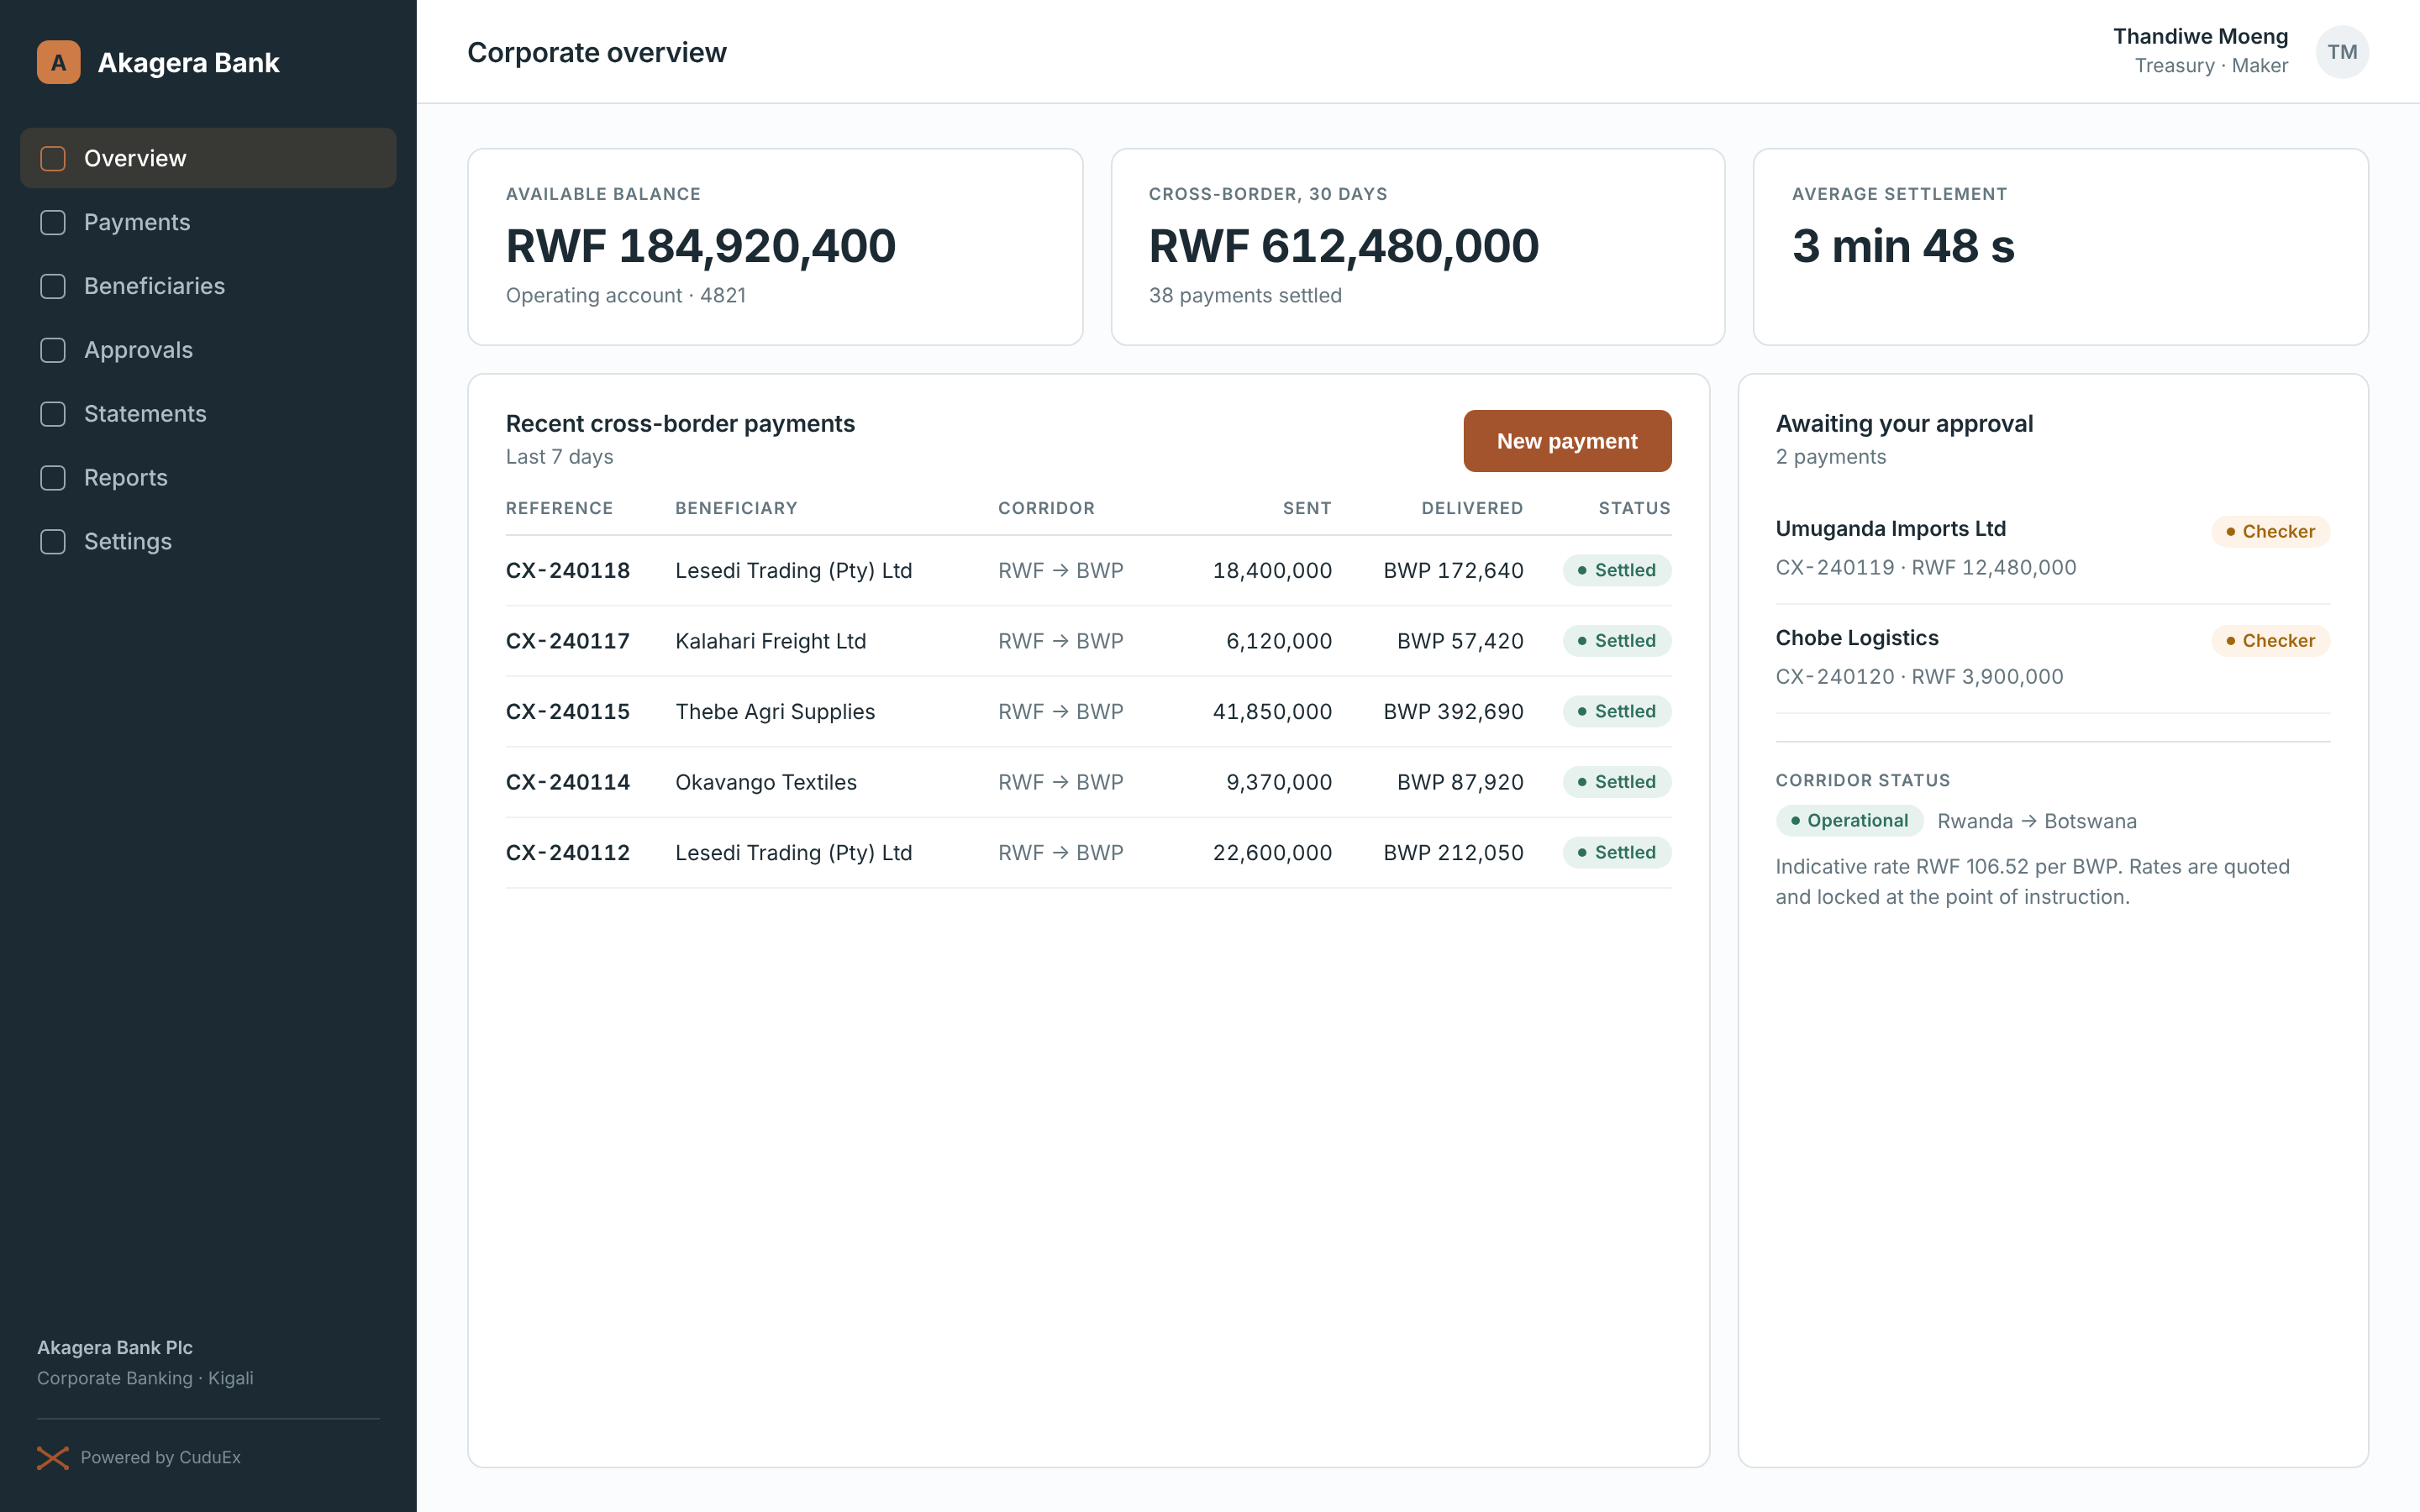
Corporate overview.
A corporate customer's view of balances, recent cross-border payments and payments awaiting approval.
Illustrative design mockup. Fictional institutions and figures; not a live product.
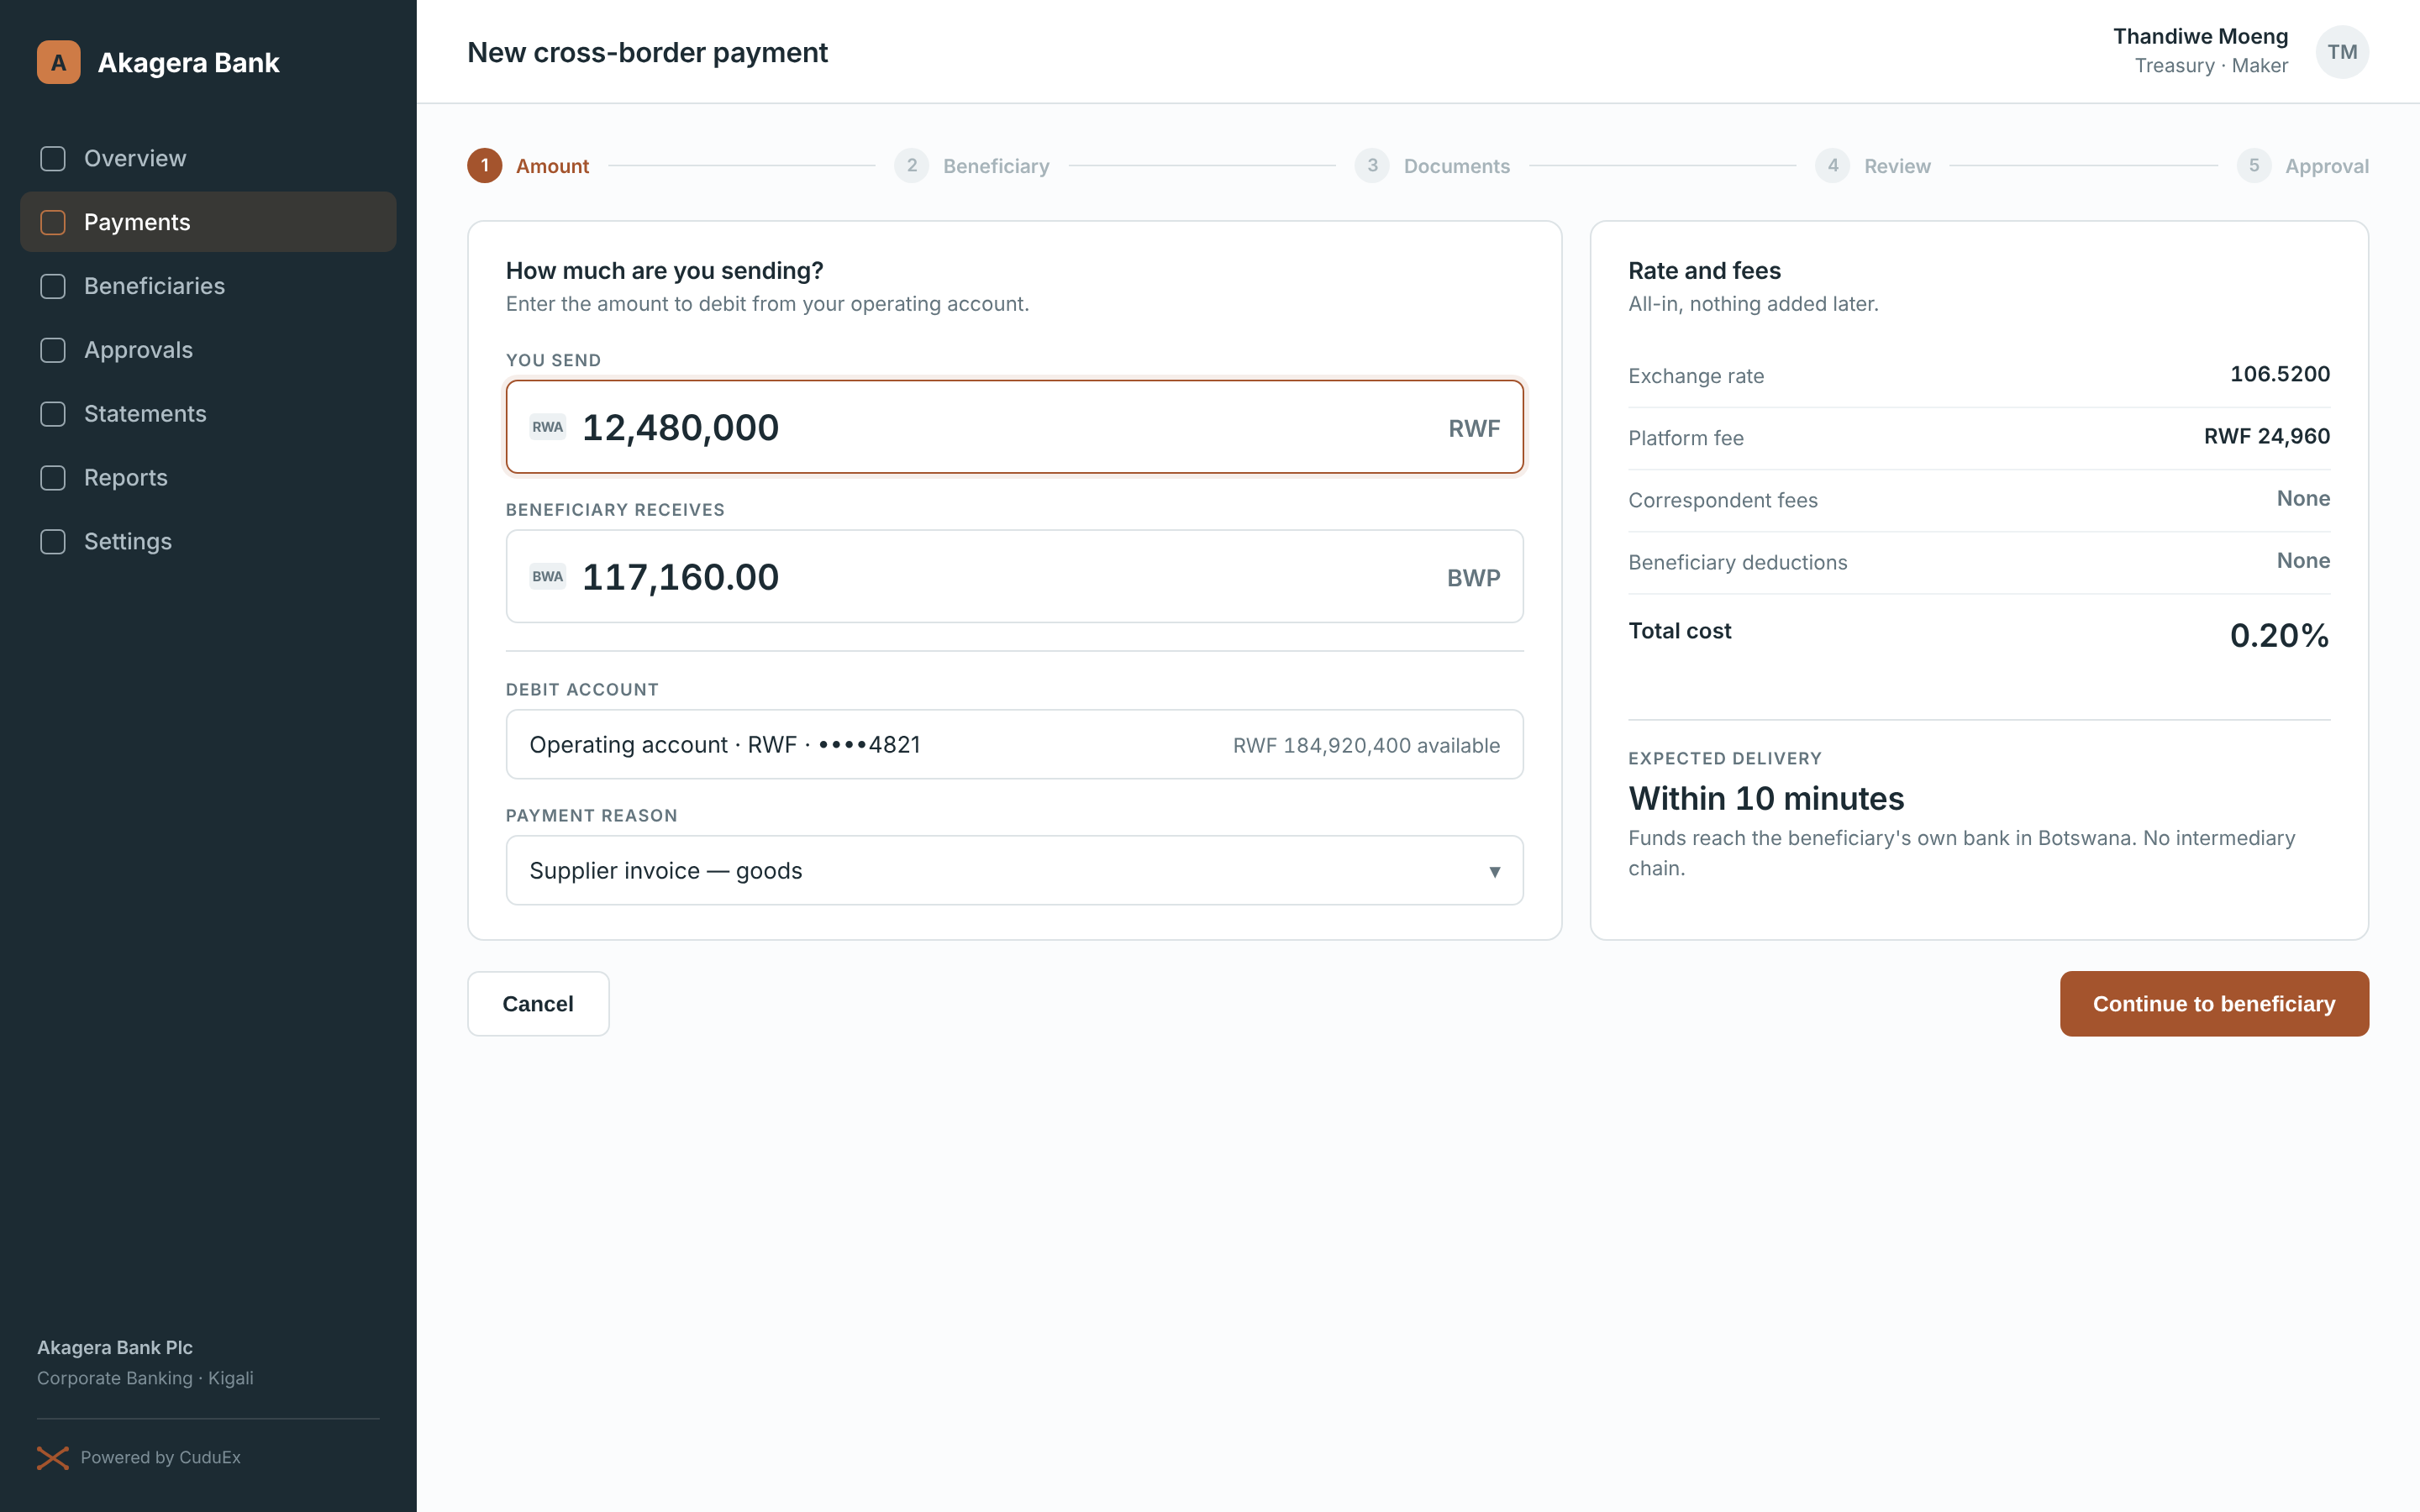
Amount and corridor.
The customer would set the amount and see the corridor, rate and fee breakdown before going further.
Illustrative design mockup. Fictional institutions and figures; not a live product.
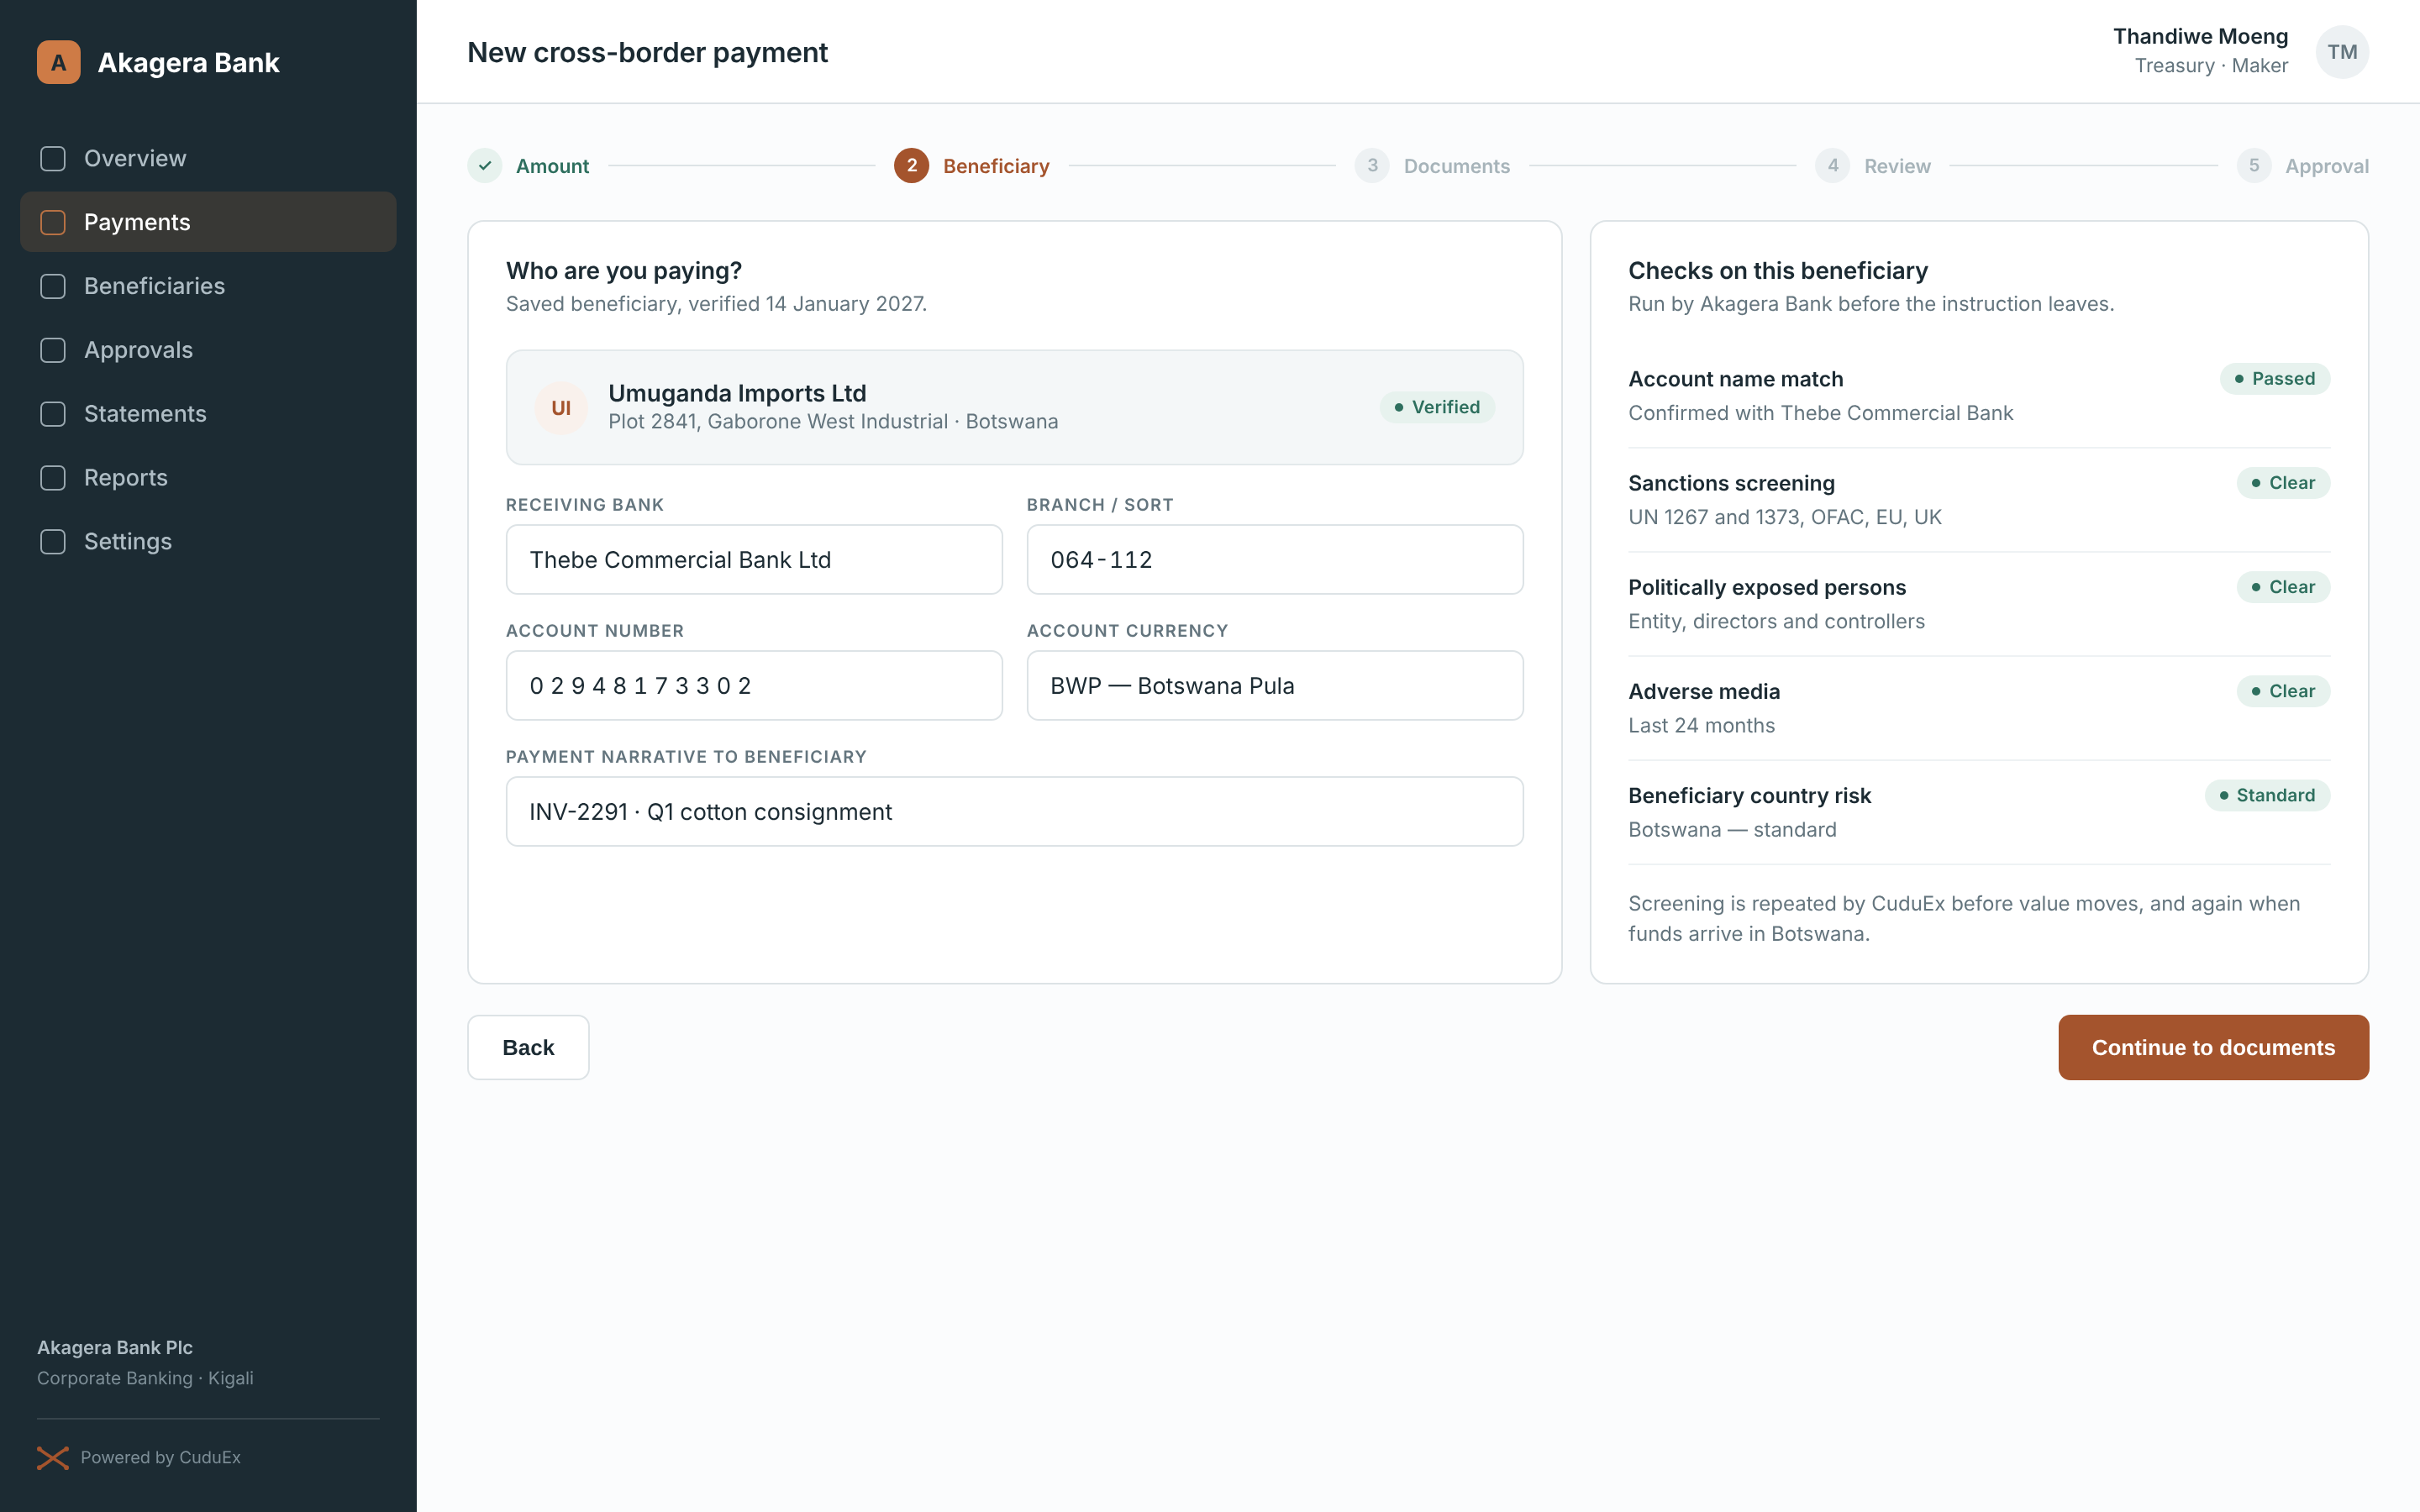
Beneficiary and checks.
Beneficiary details would sit beside the checks run on them, such as account name match and sanctions screening.
Illustrative design mockup. Fictional institutions and figures; not a live product.
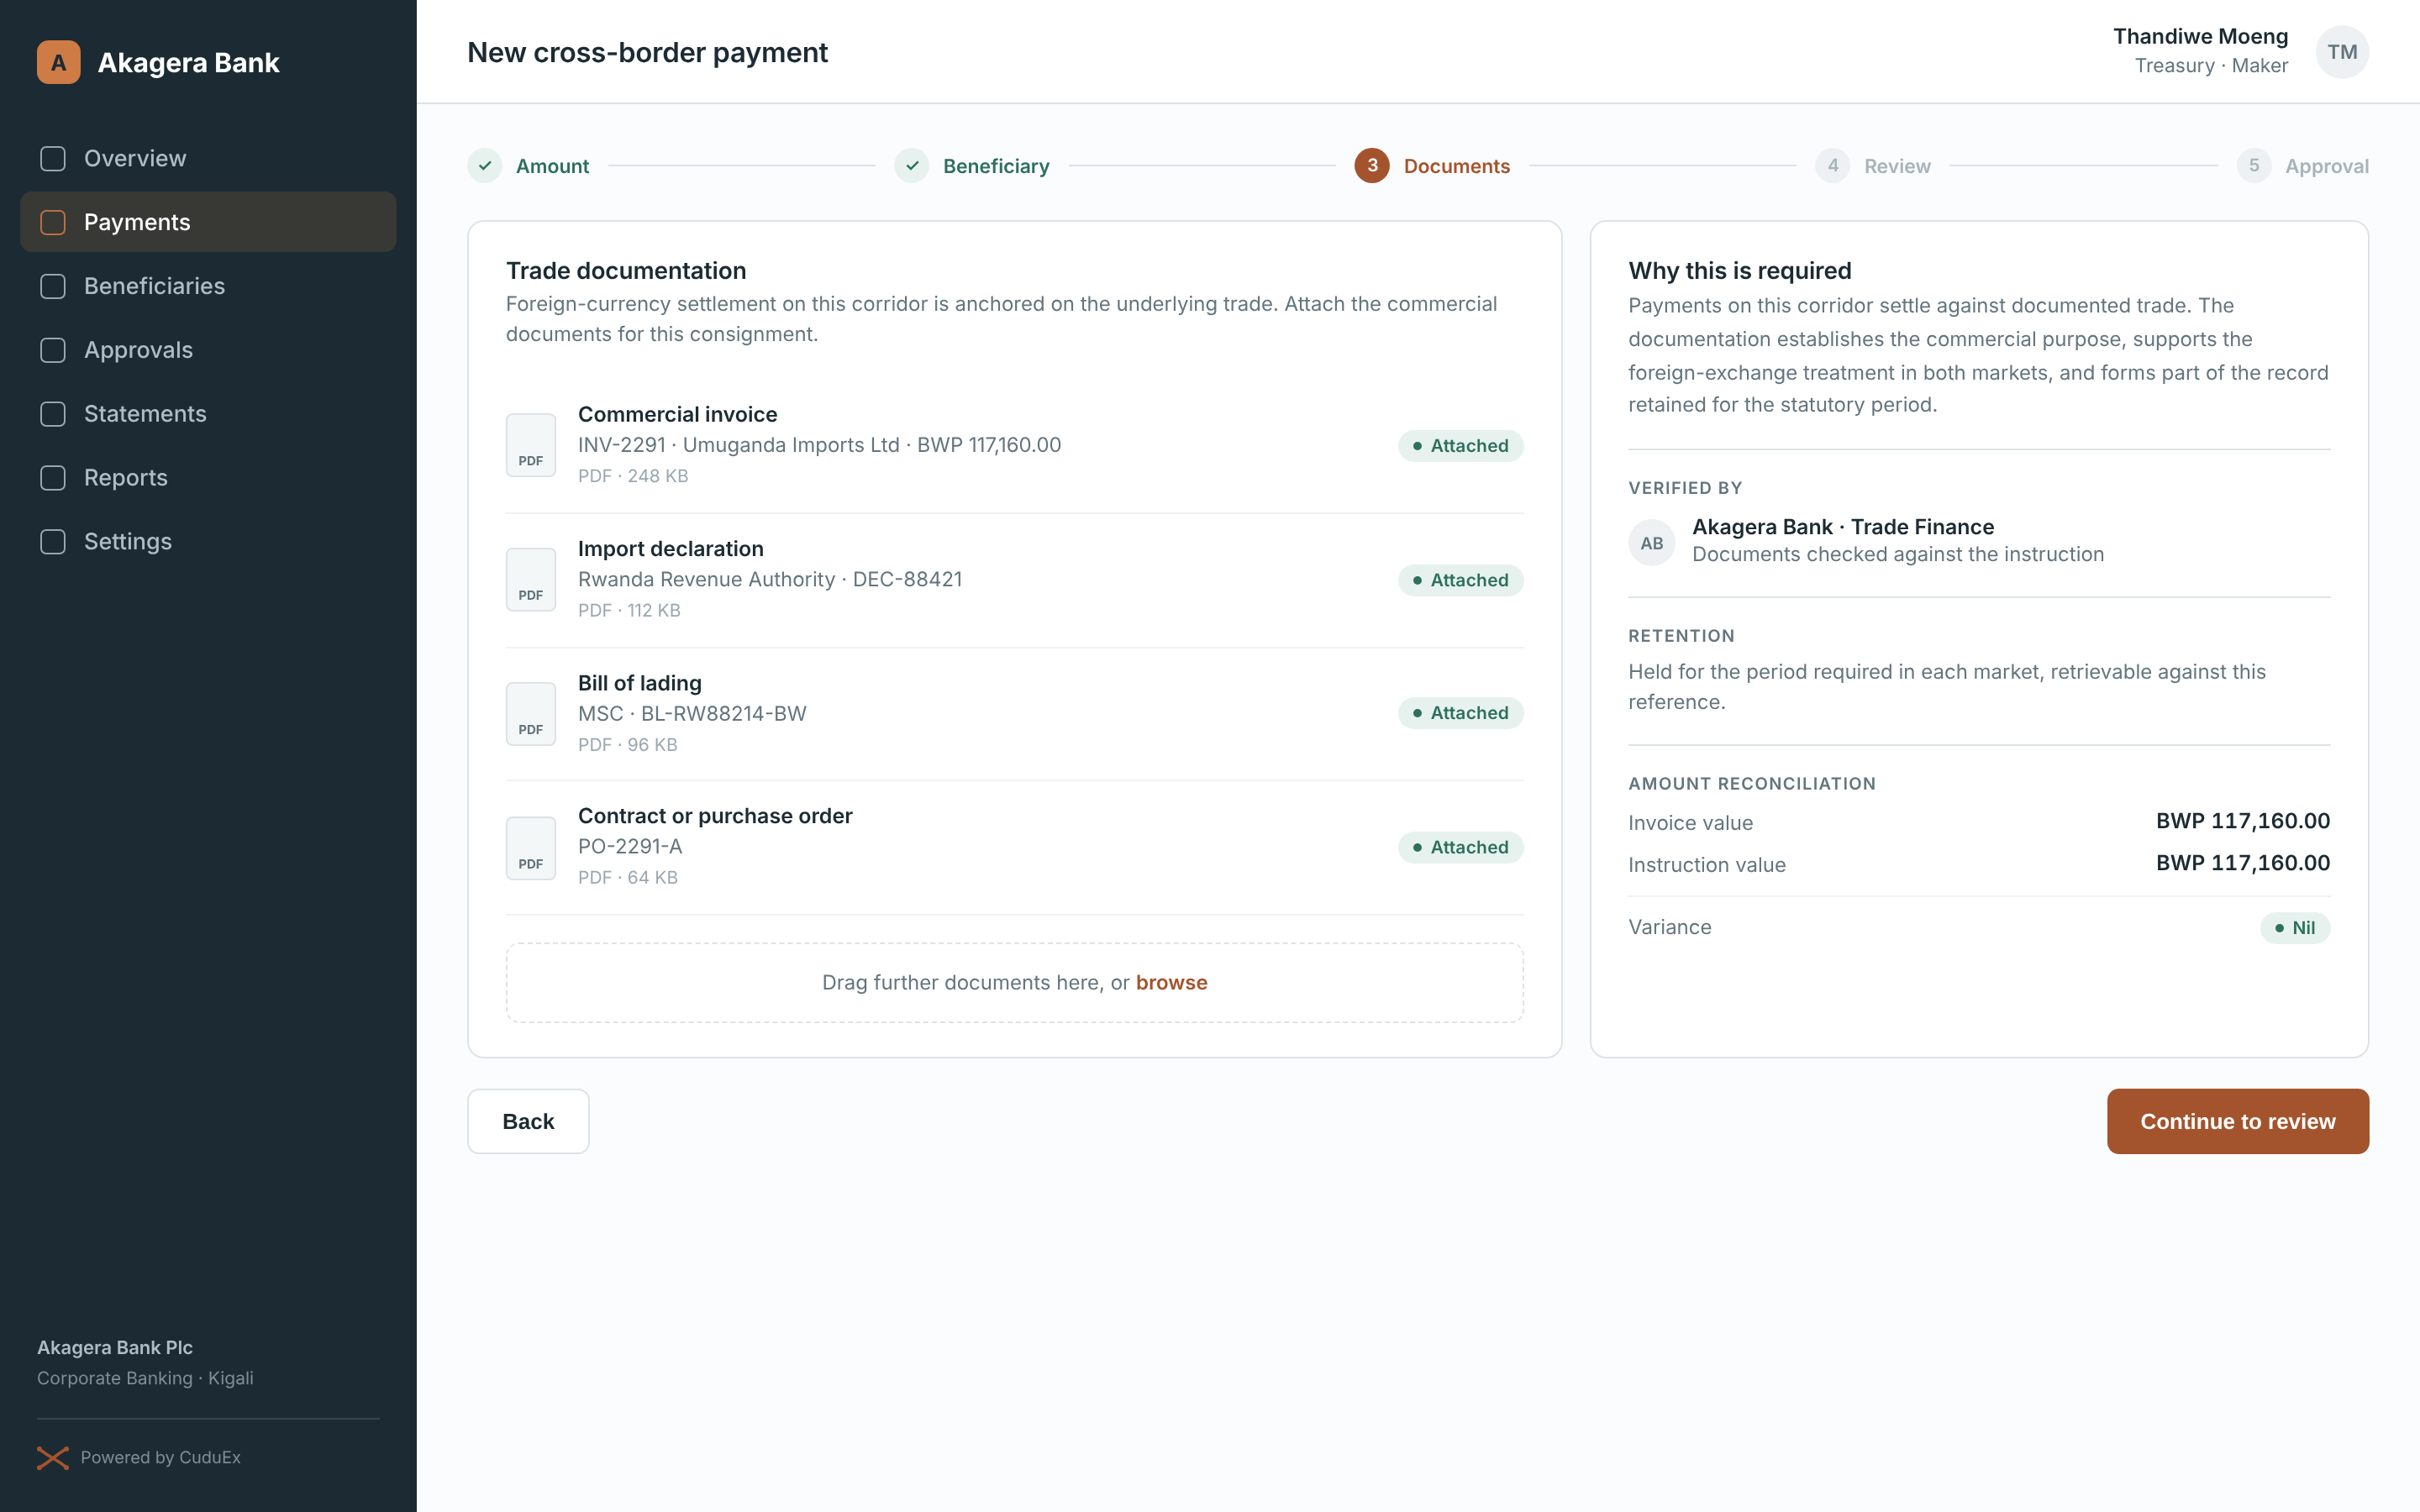
Trade documentation.
Commercial documents would be attached to the instruction and checked against it, anchoring the payment on the underlying trade.
Illustrative design mockup. Fictional institutions and figures; not a live product.
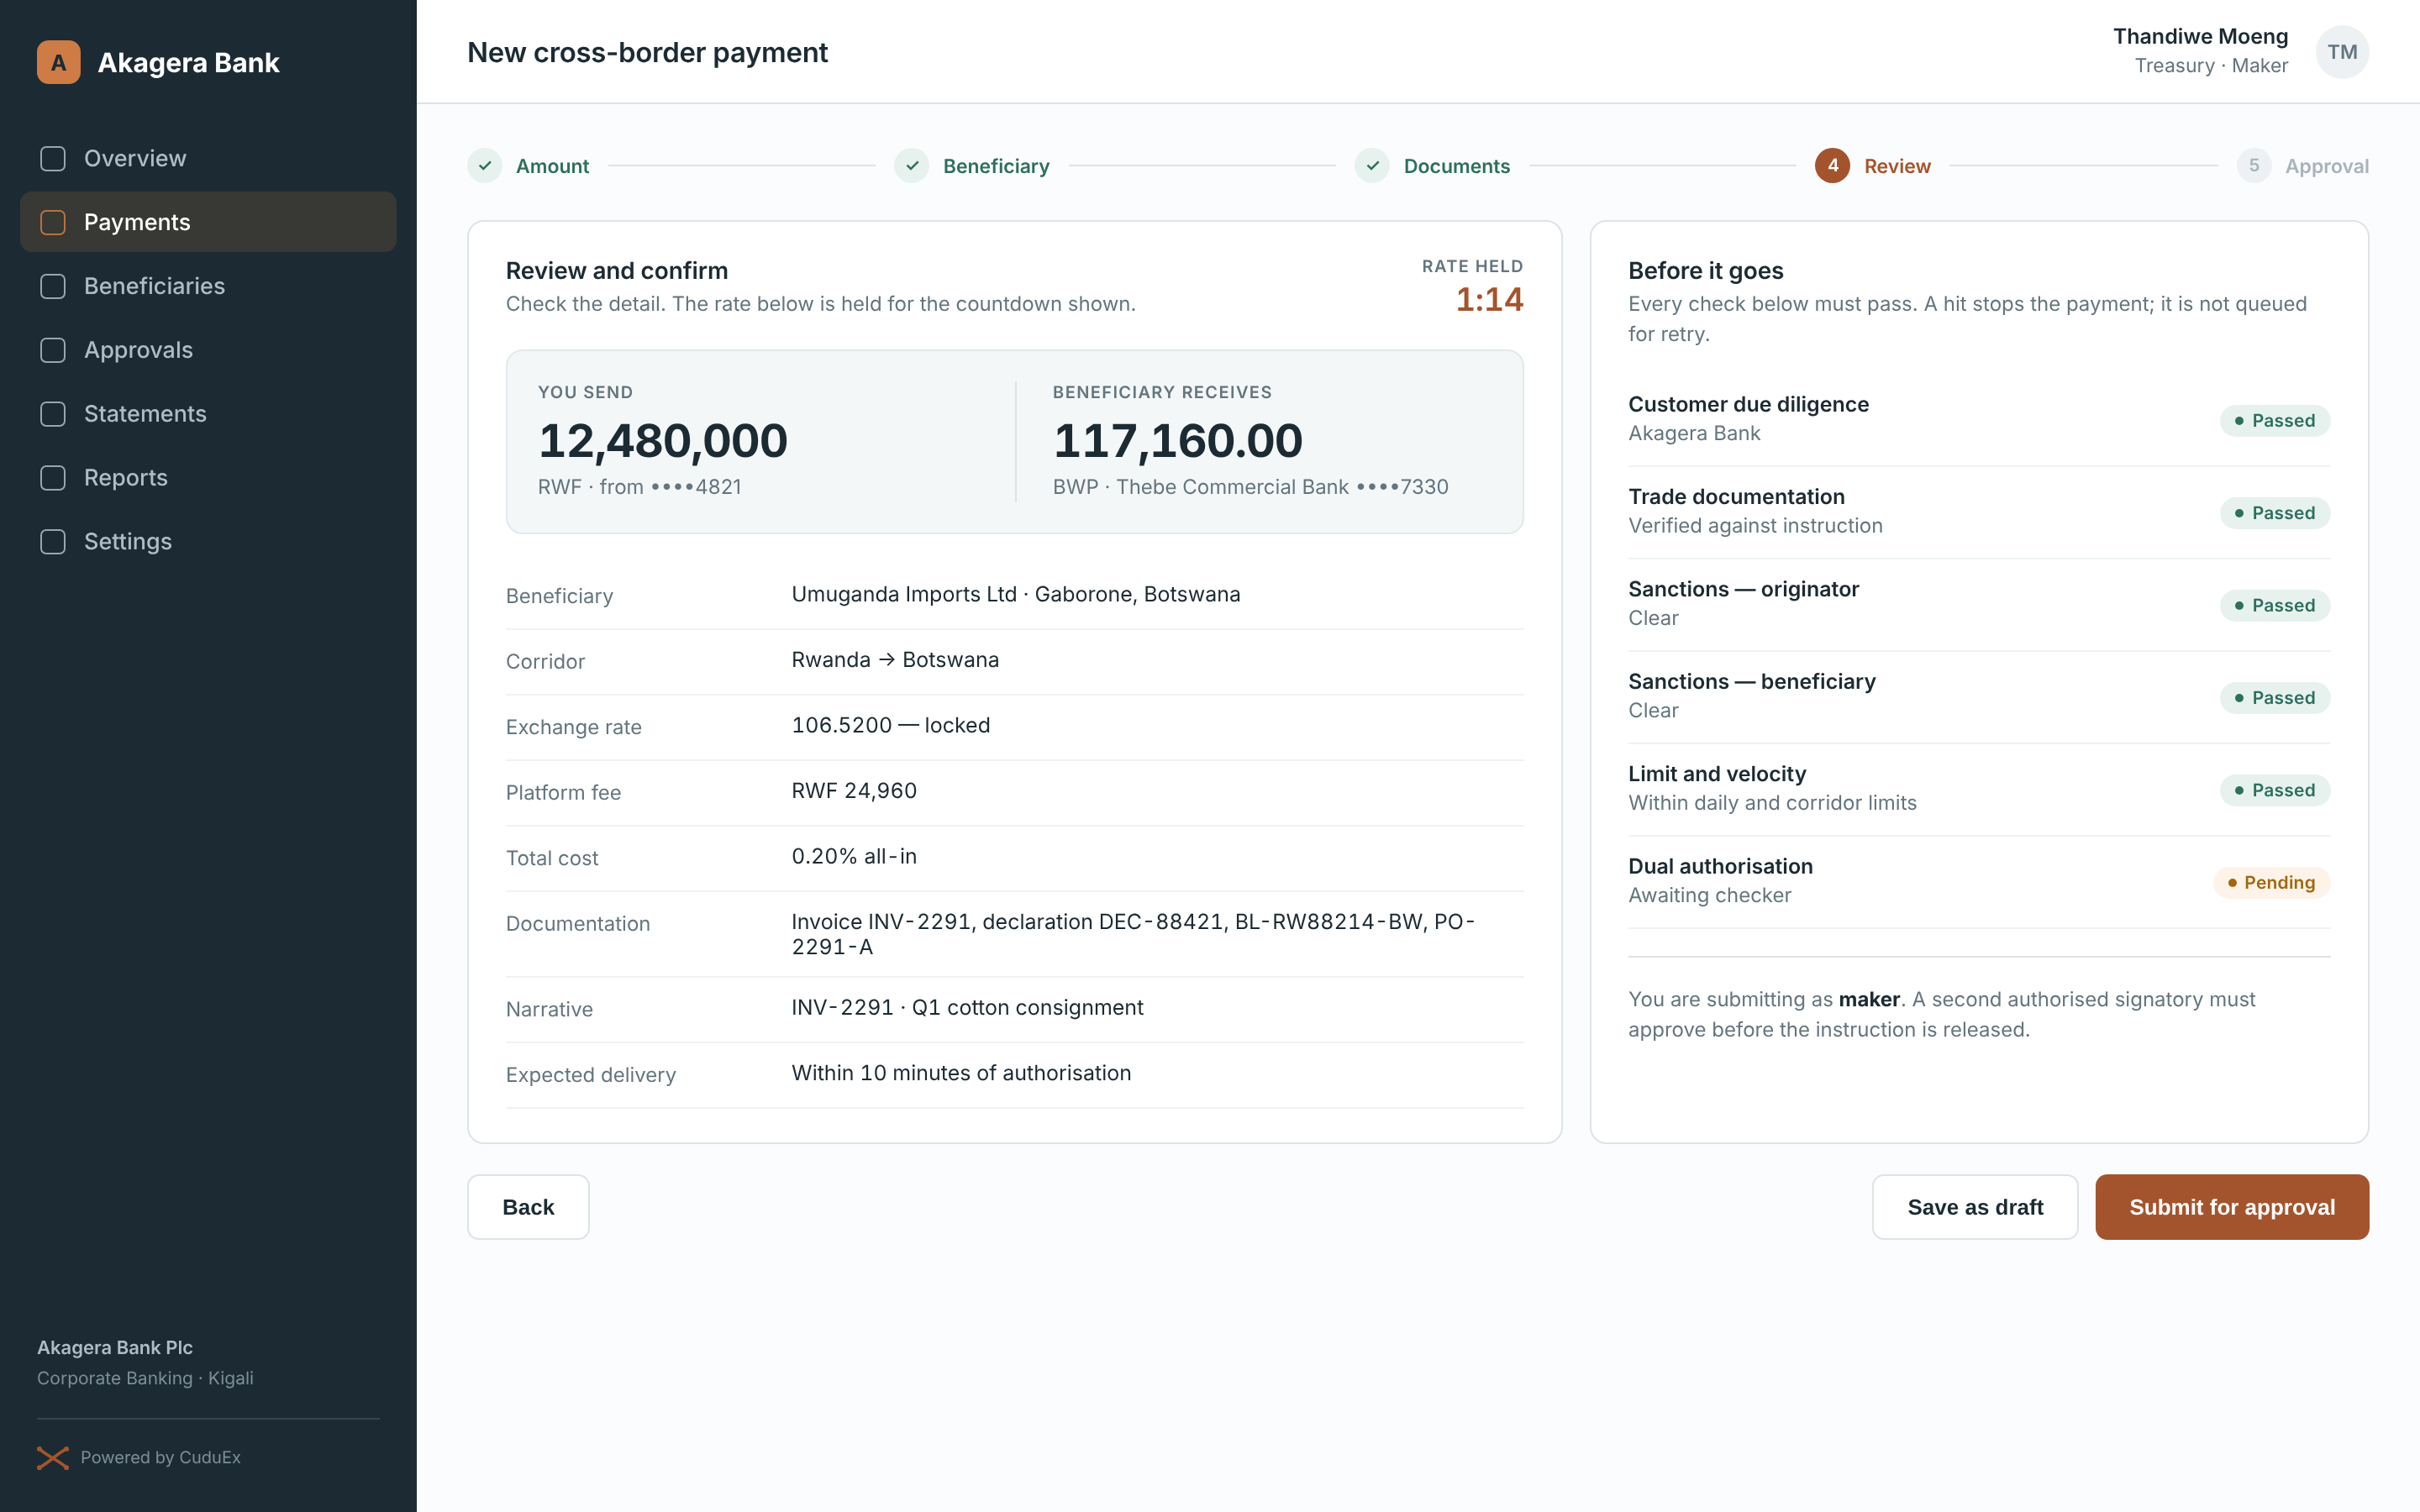
Review and confirm.
The customer would review the full instruction, with the rate held on a countdown and the checks that must pass before it goes.
Illustrative design mockup. Fictional institutions and figures; not a live product.
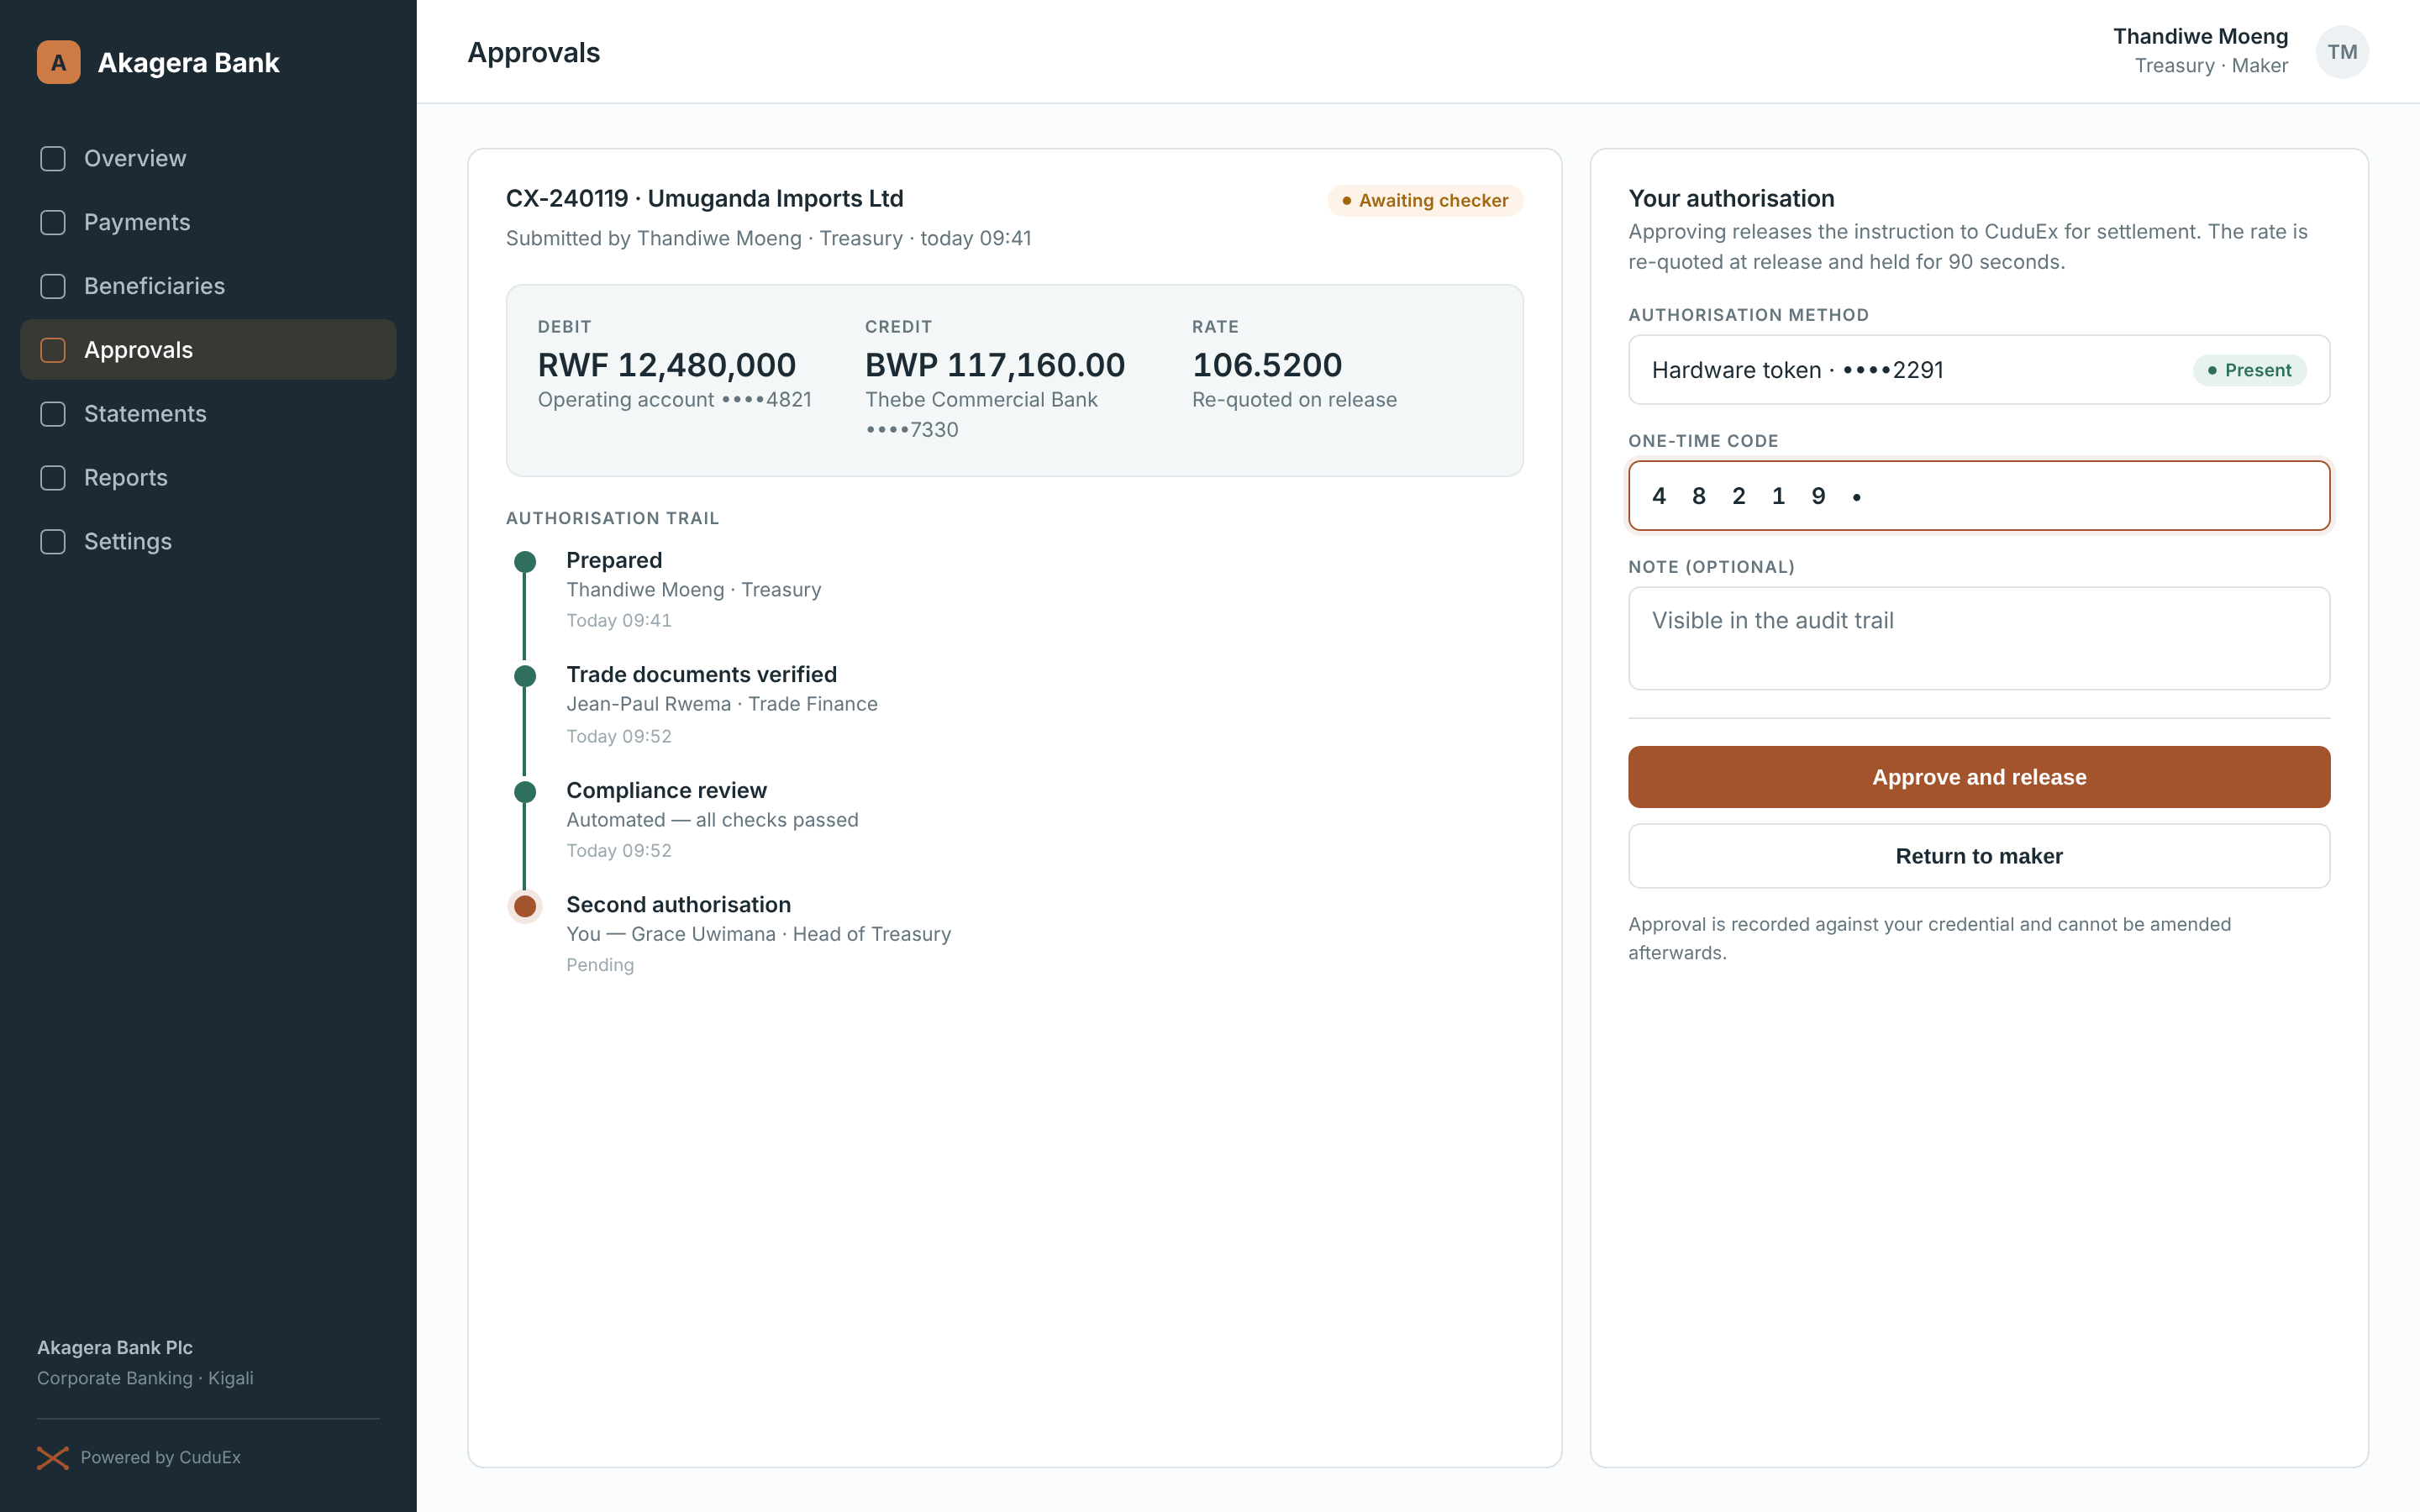
Second authorisation.
A second authorised signatory would approve before release, with each step recorded in a maker-checker trail.
Illustrative design mockup. Fictional institutions and figures; not a live product.
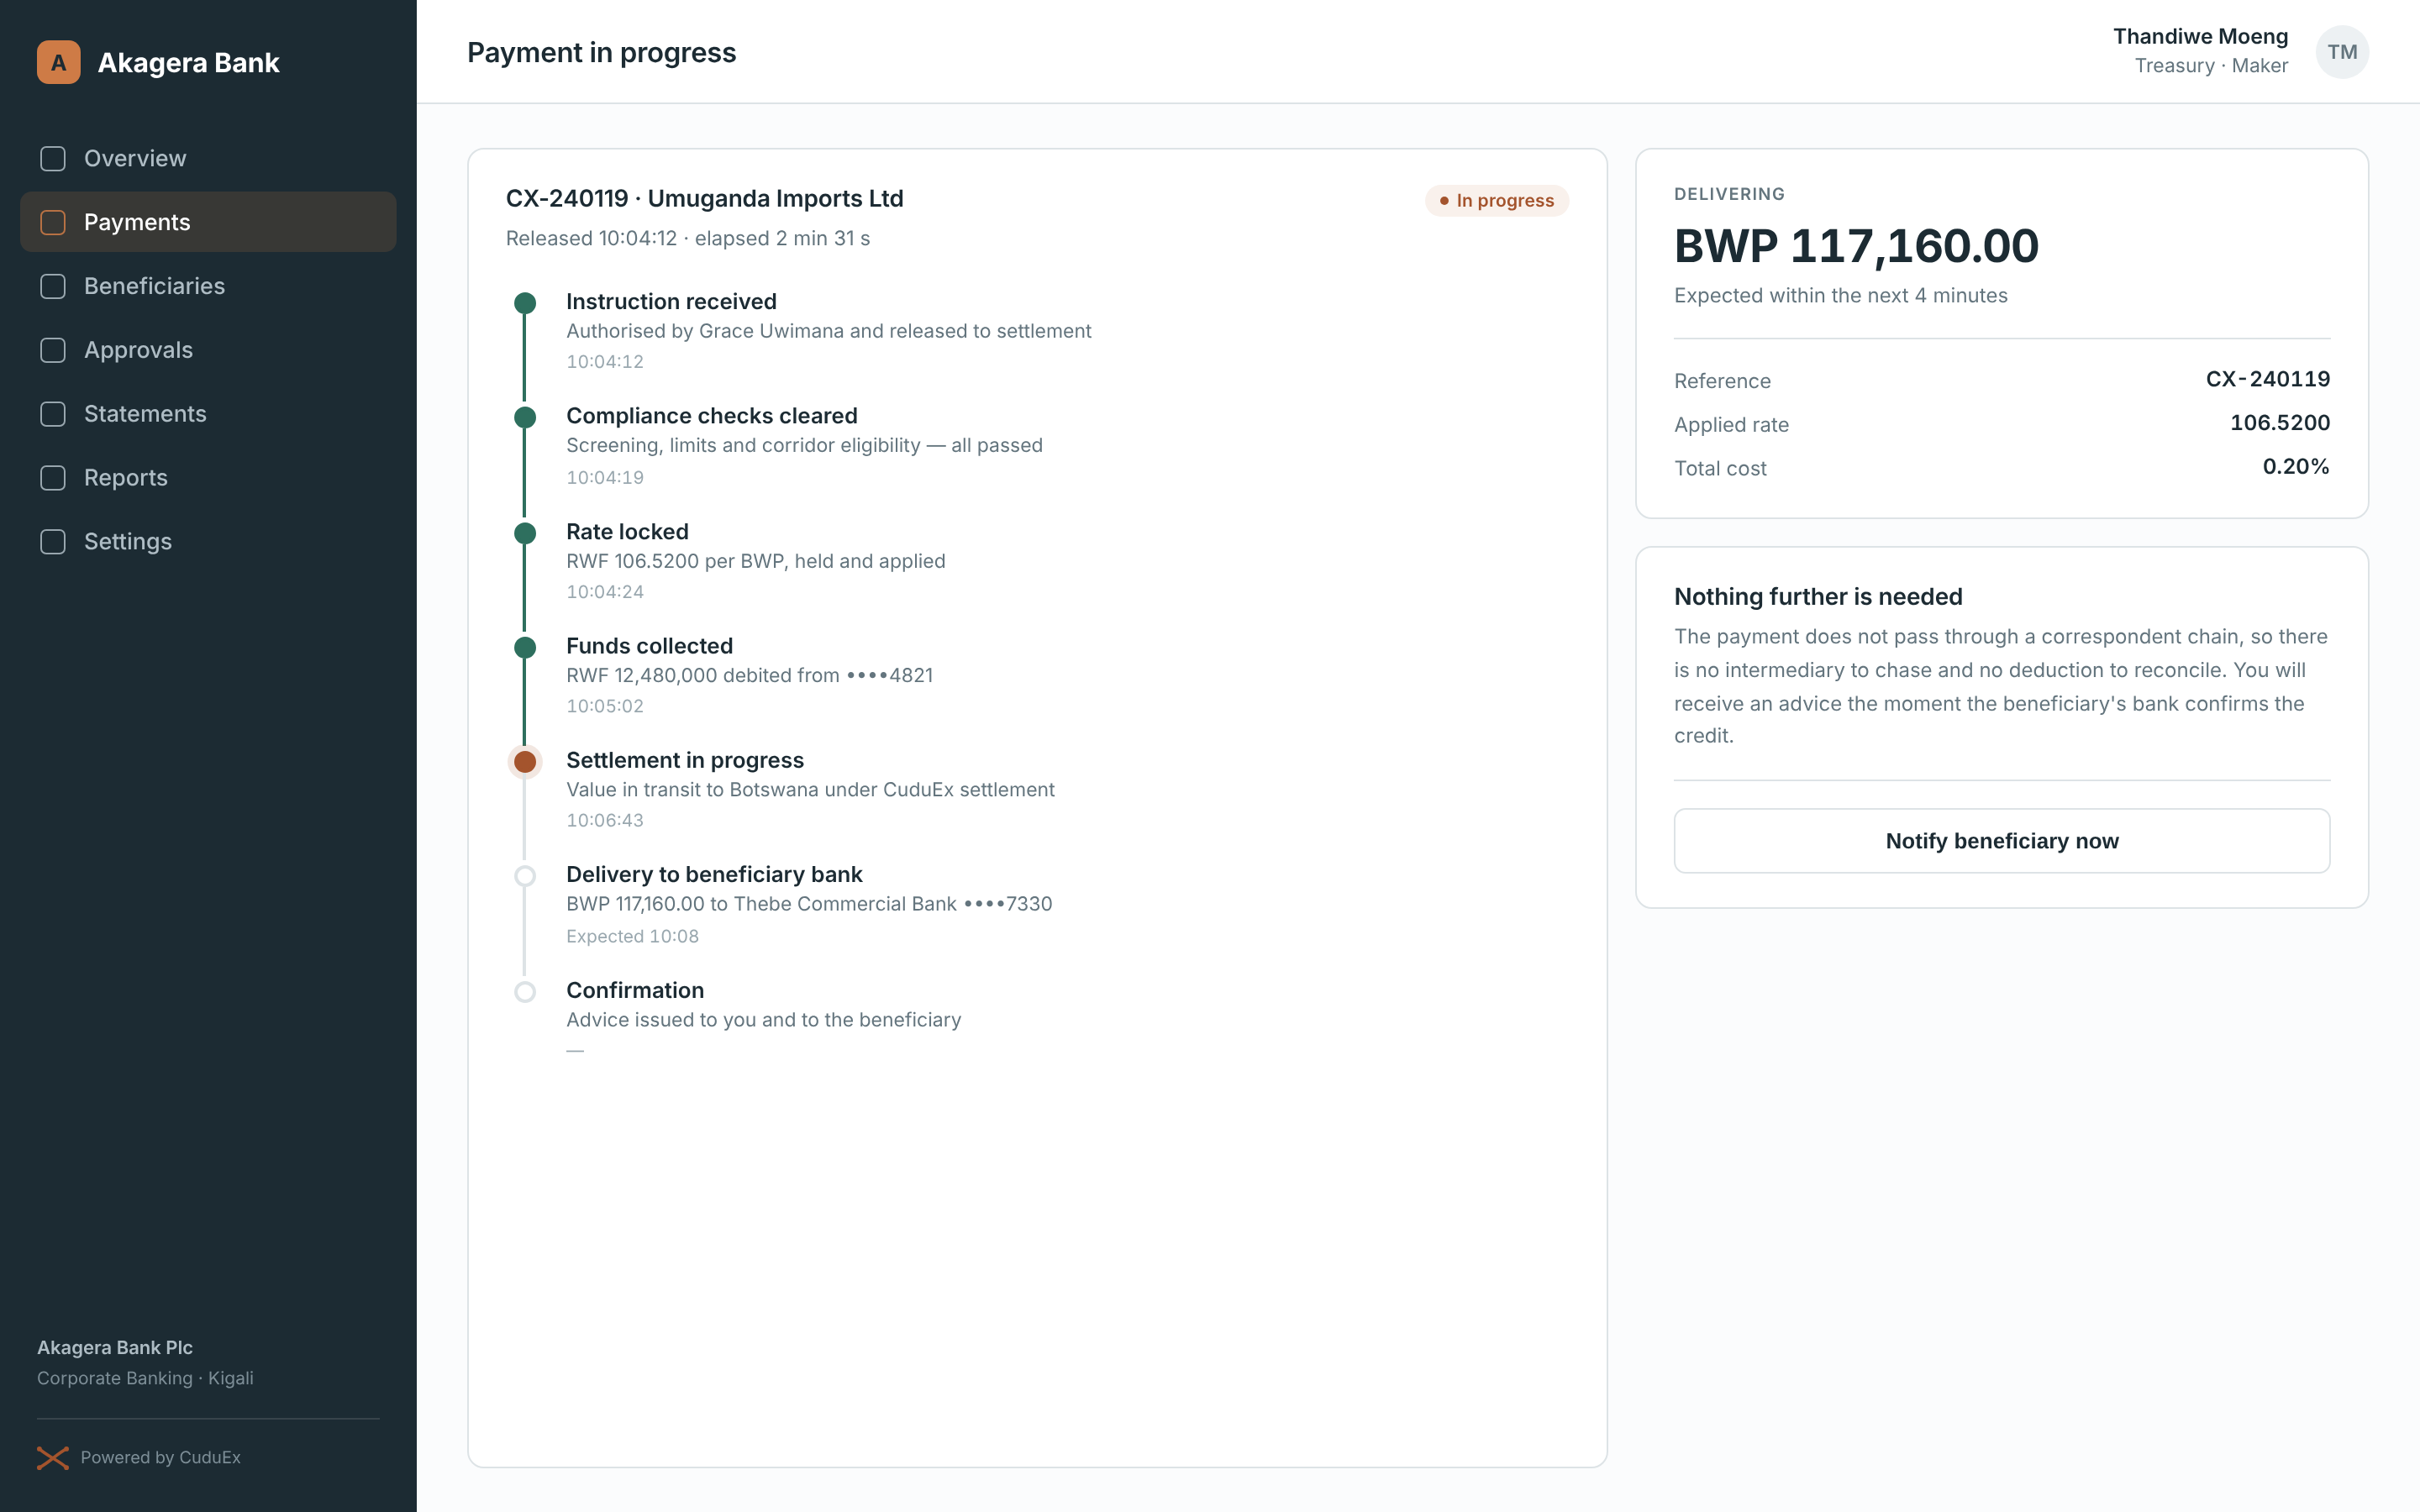
Settlement tracker.
The customer would follow the payment stage by stage, in customer-facing wording.
Illustrative design mockup. Fictional institutions and figures; not a live product.
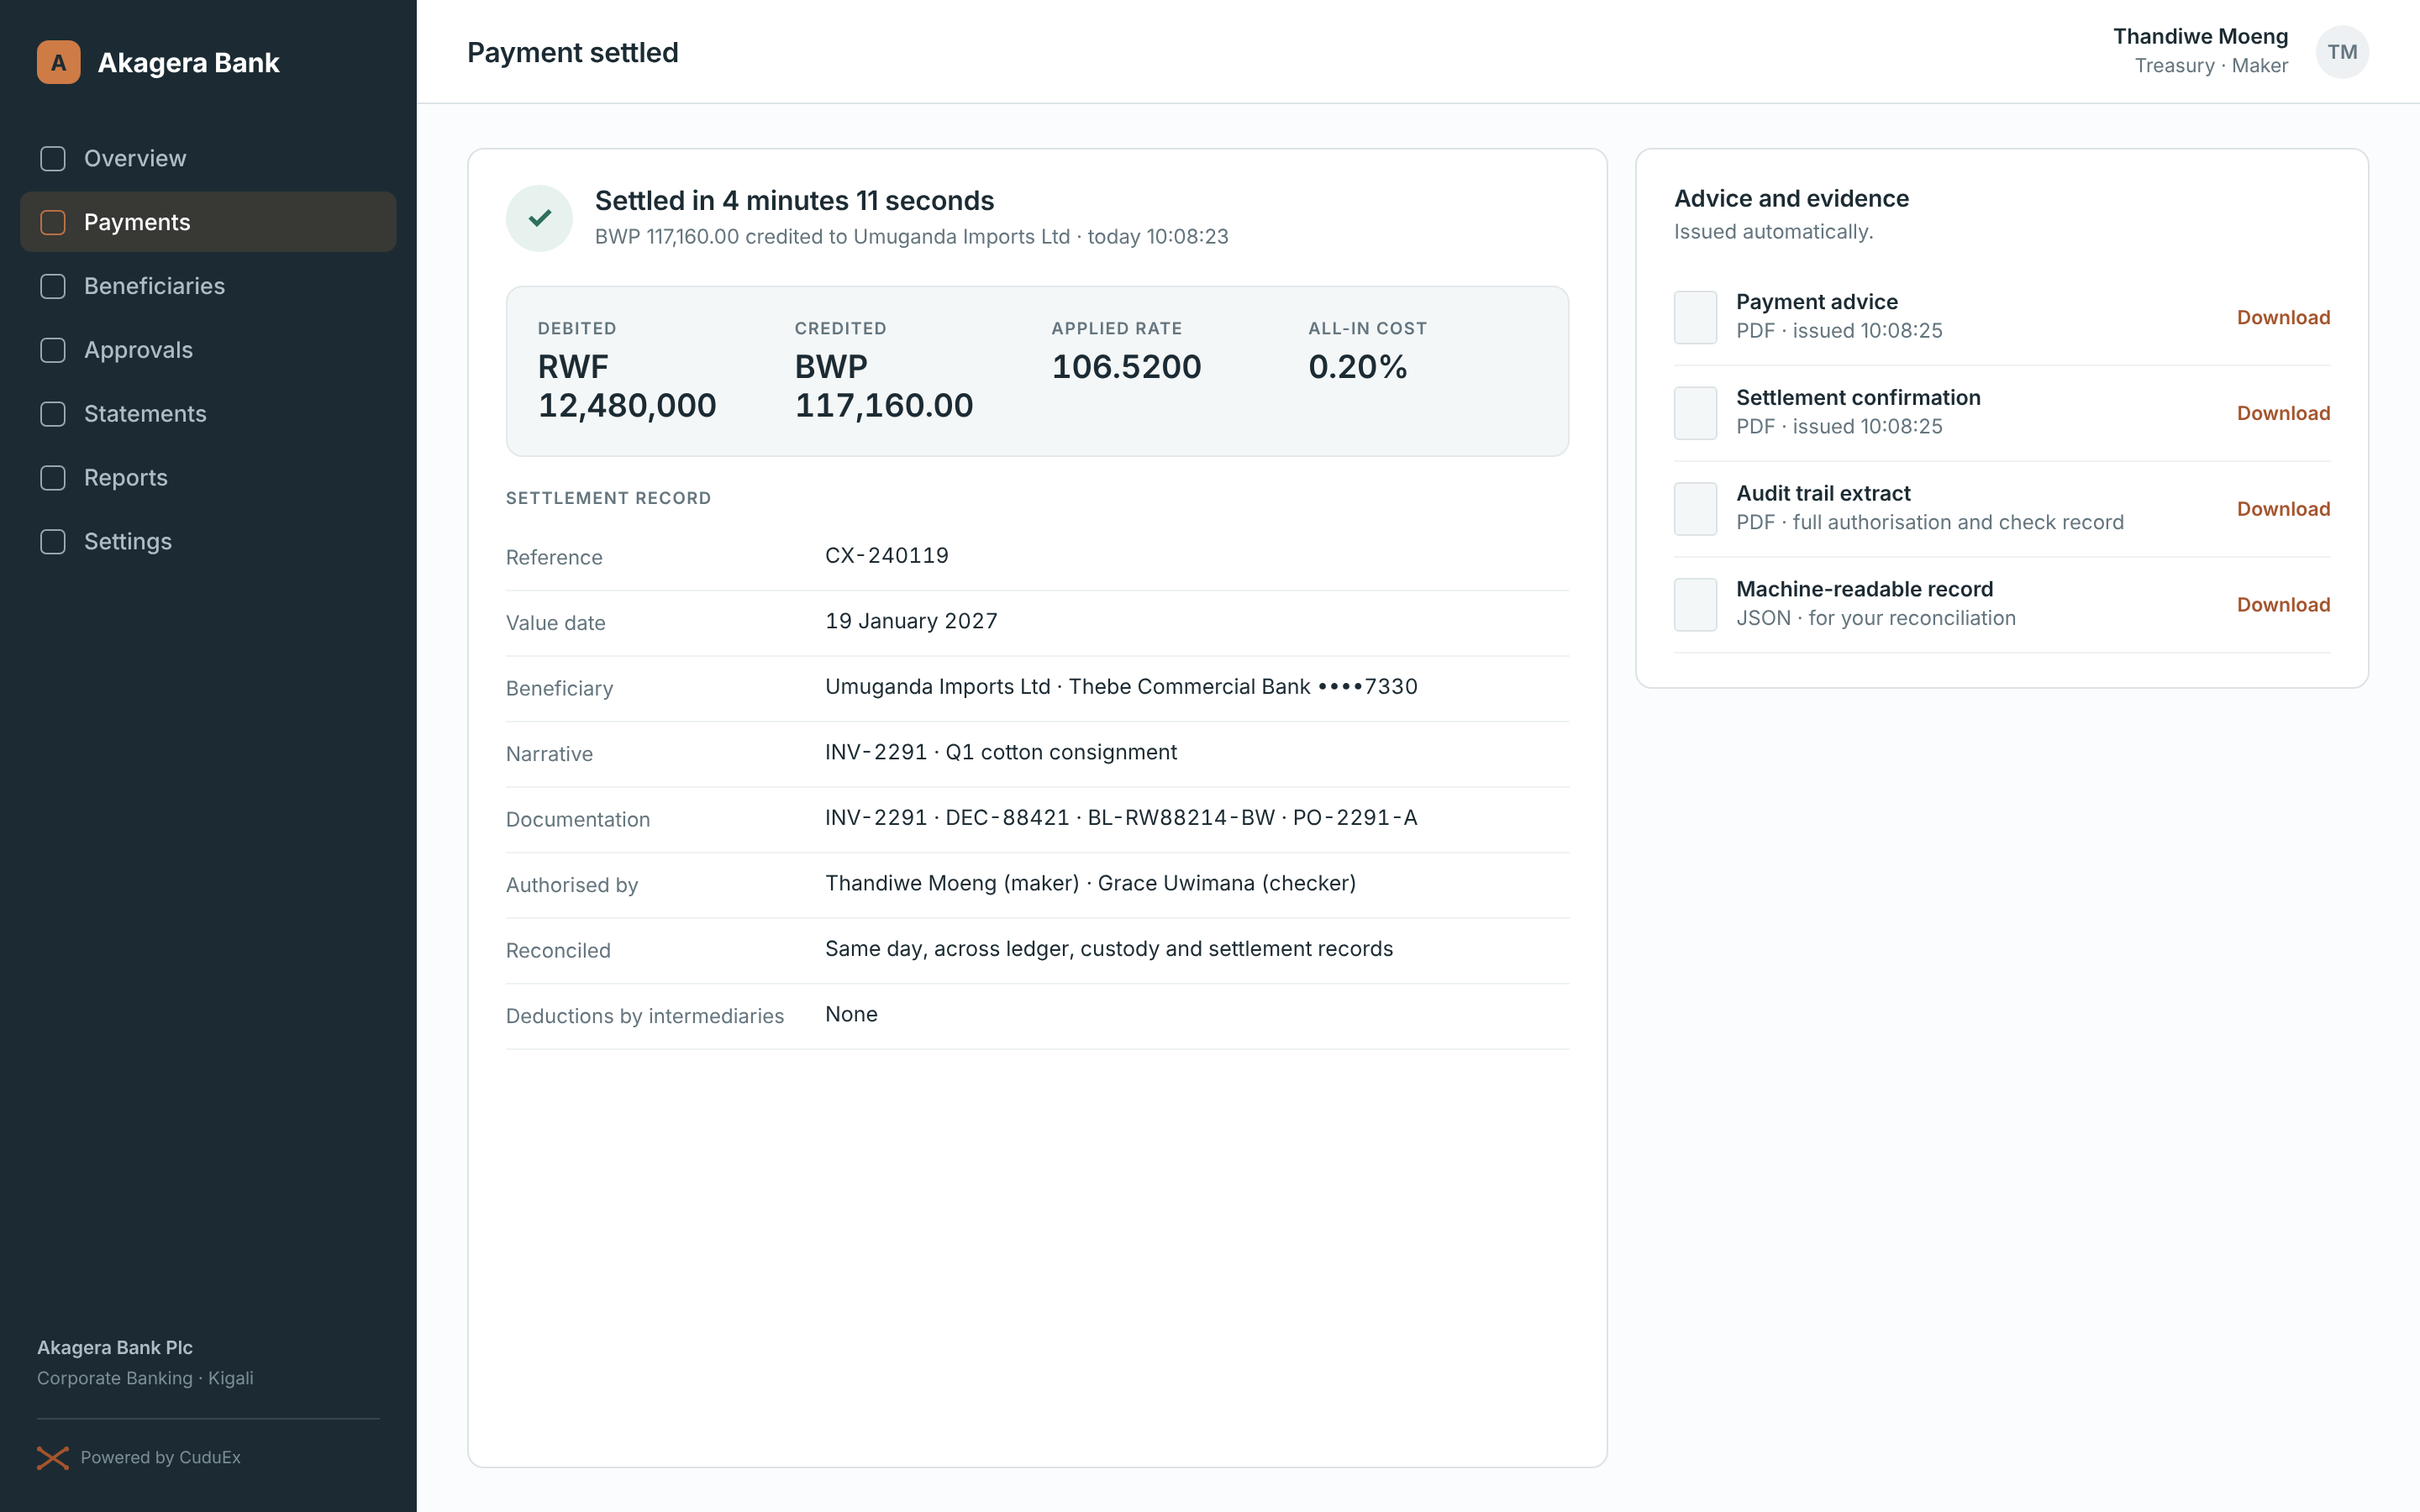
Settled receipt.
A settlement record would close the journey, with the advice and evidence documents behind it.
Illustrative design mockup. Fictional institutions and figures; not a live product.
A personal remittance, in the partner's own app.
How a household support payment could look to a partner institution's end customer, carrying the partner's brand.
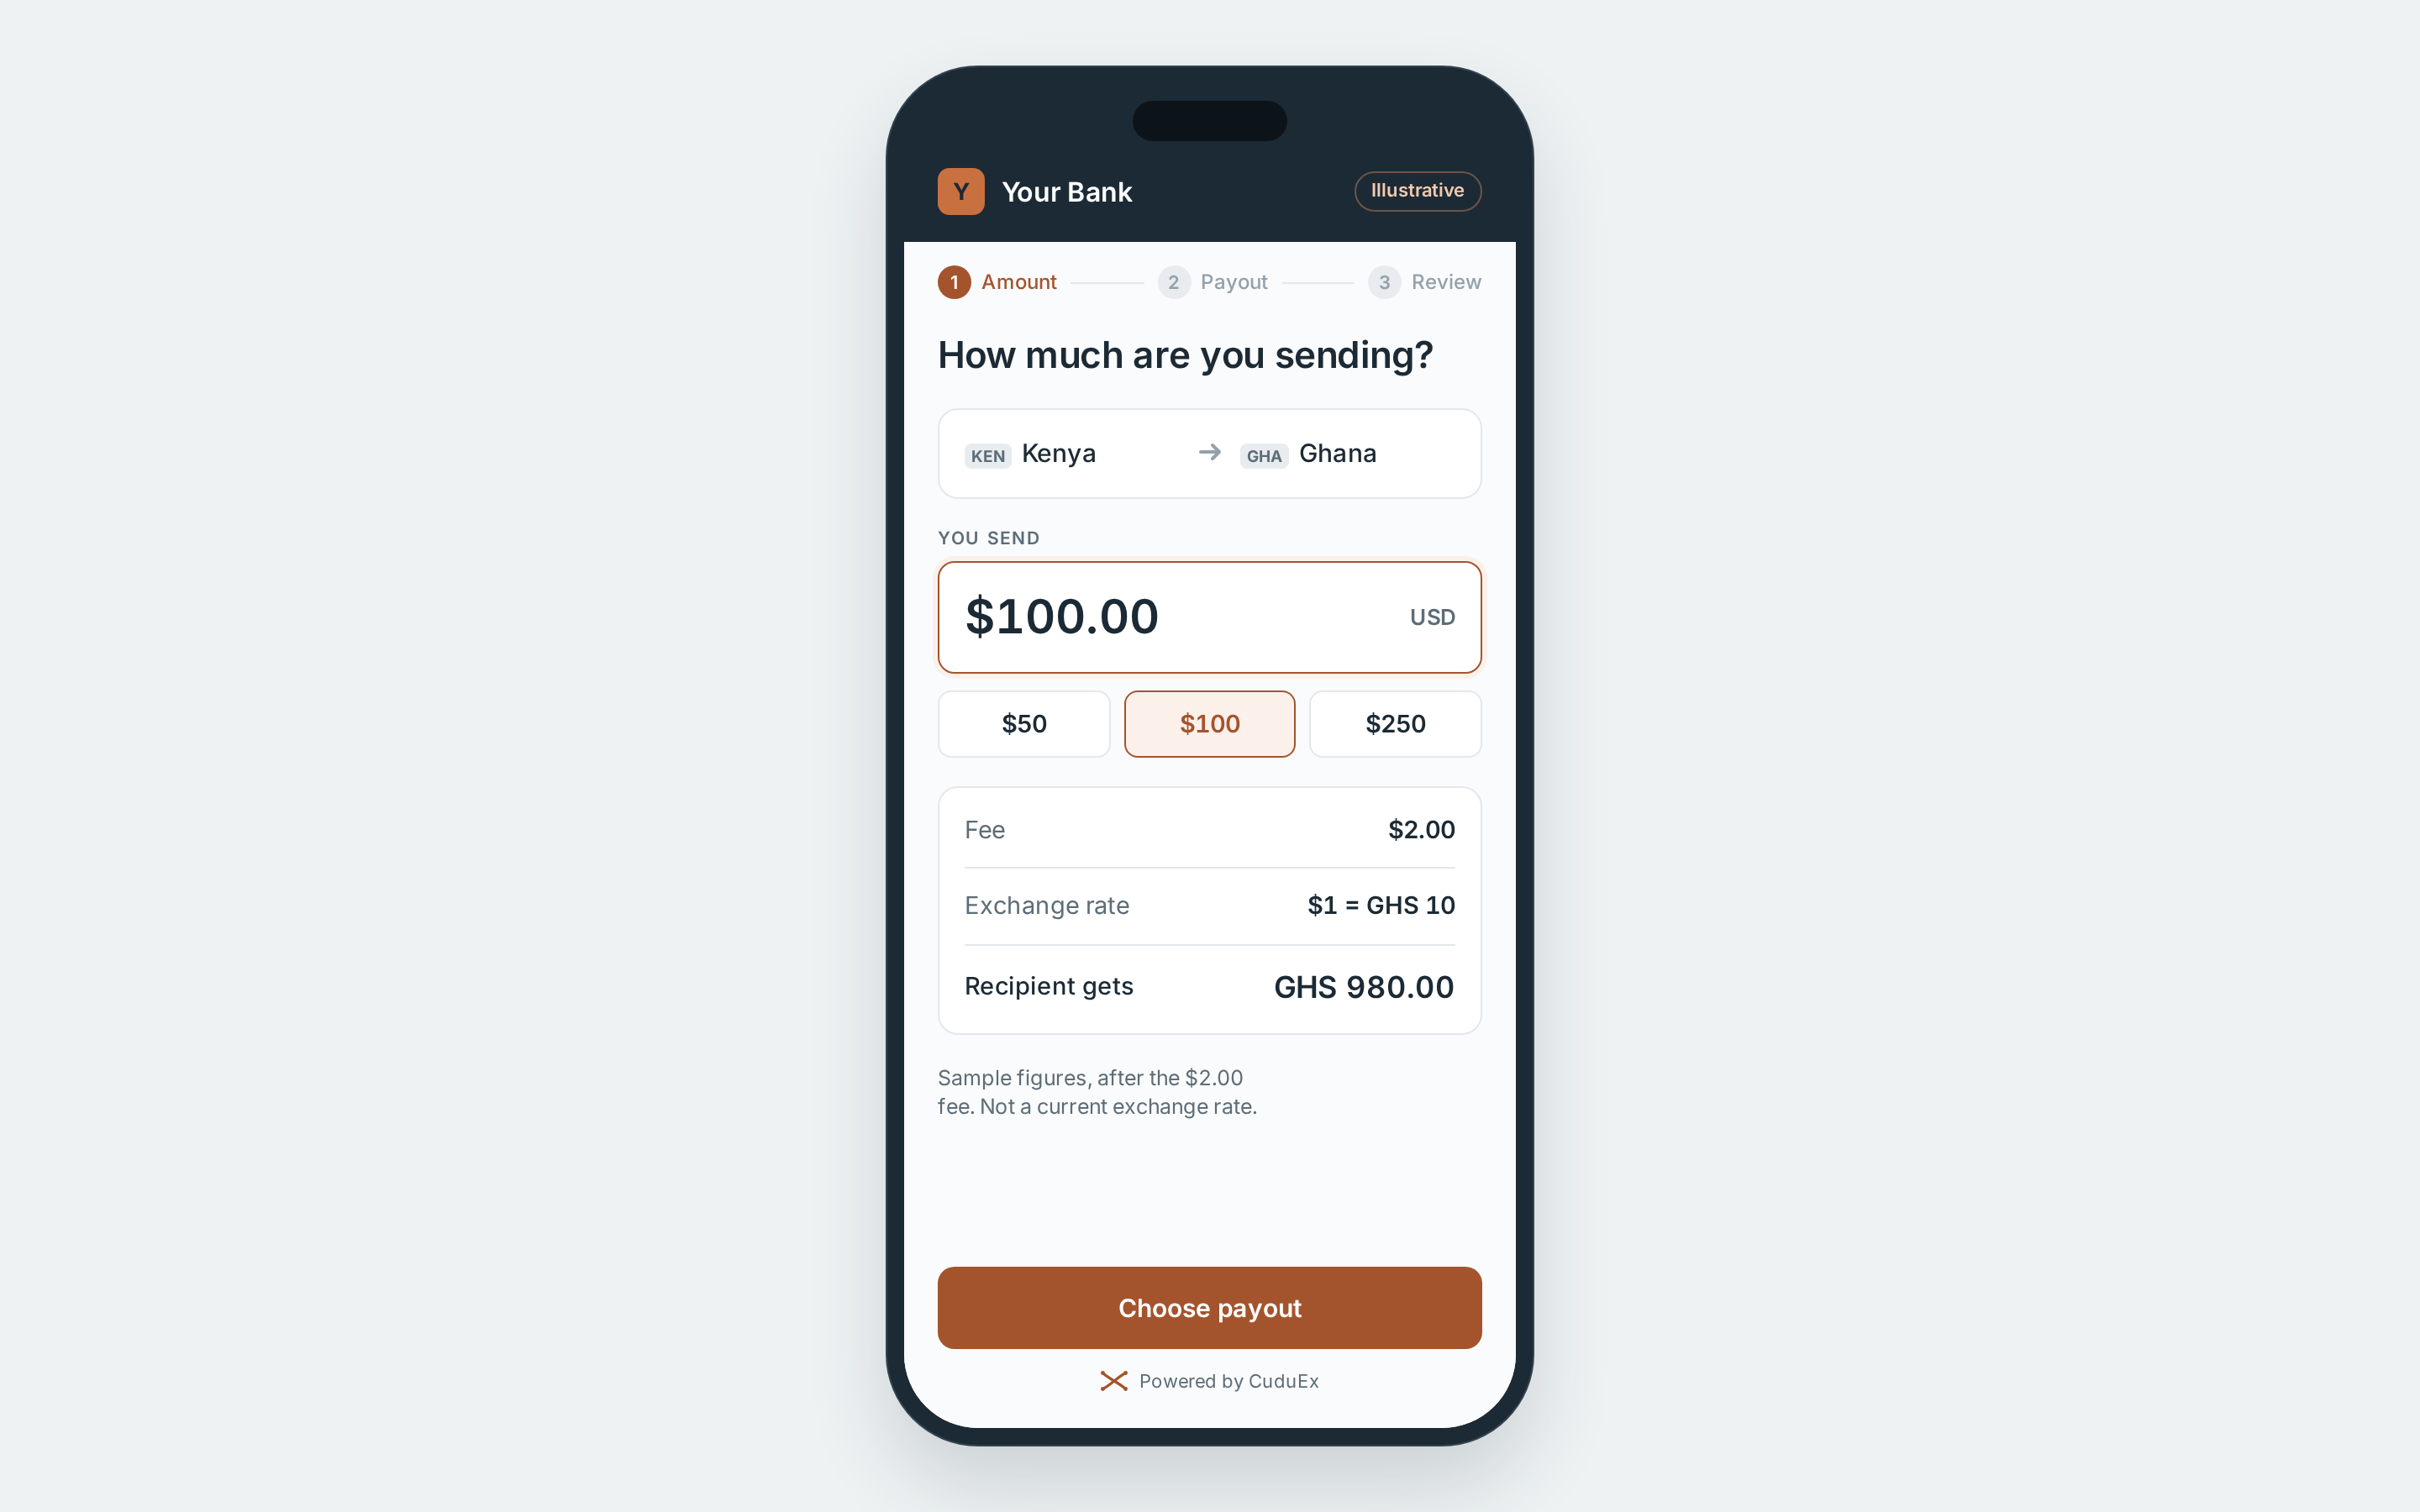
Amount.
The sender would choose an amount and see the fee, the exchange rate and what the recipient would get.
Illustrative design mockup. Fictional institutions and figures; not a live product.
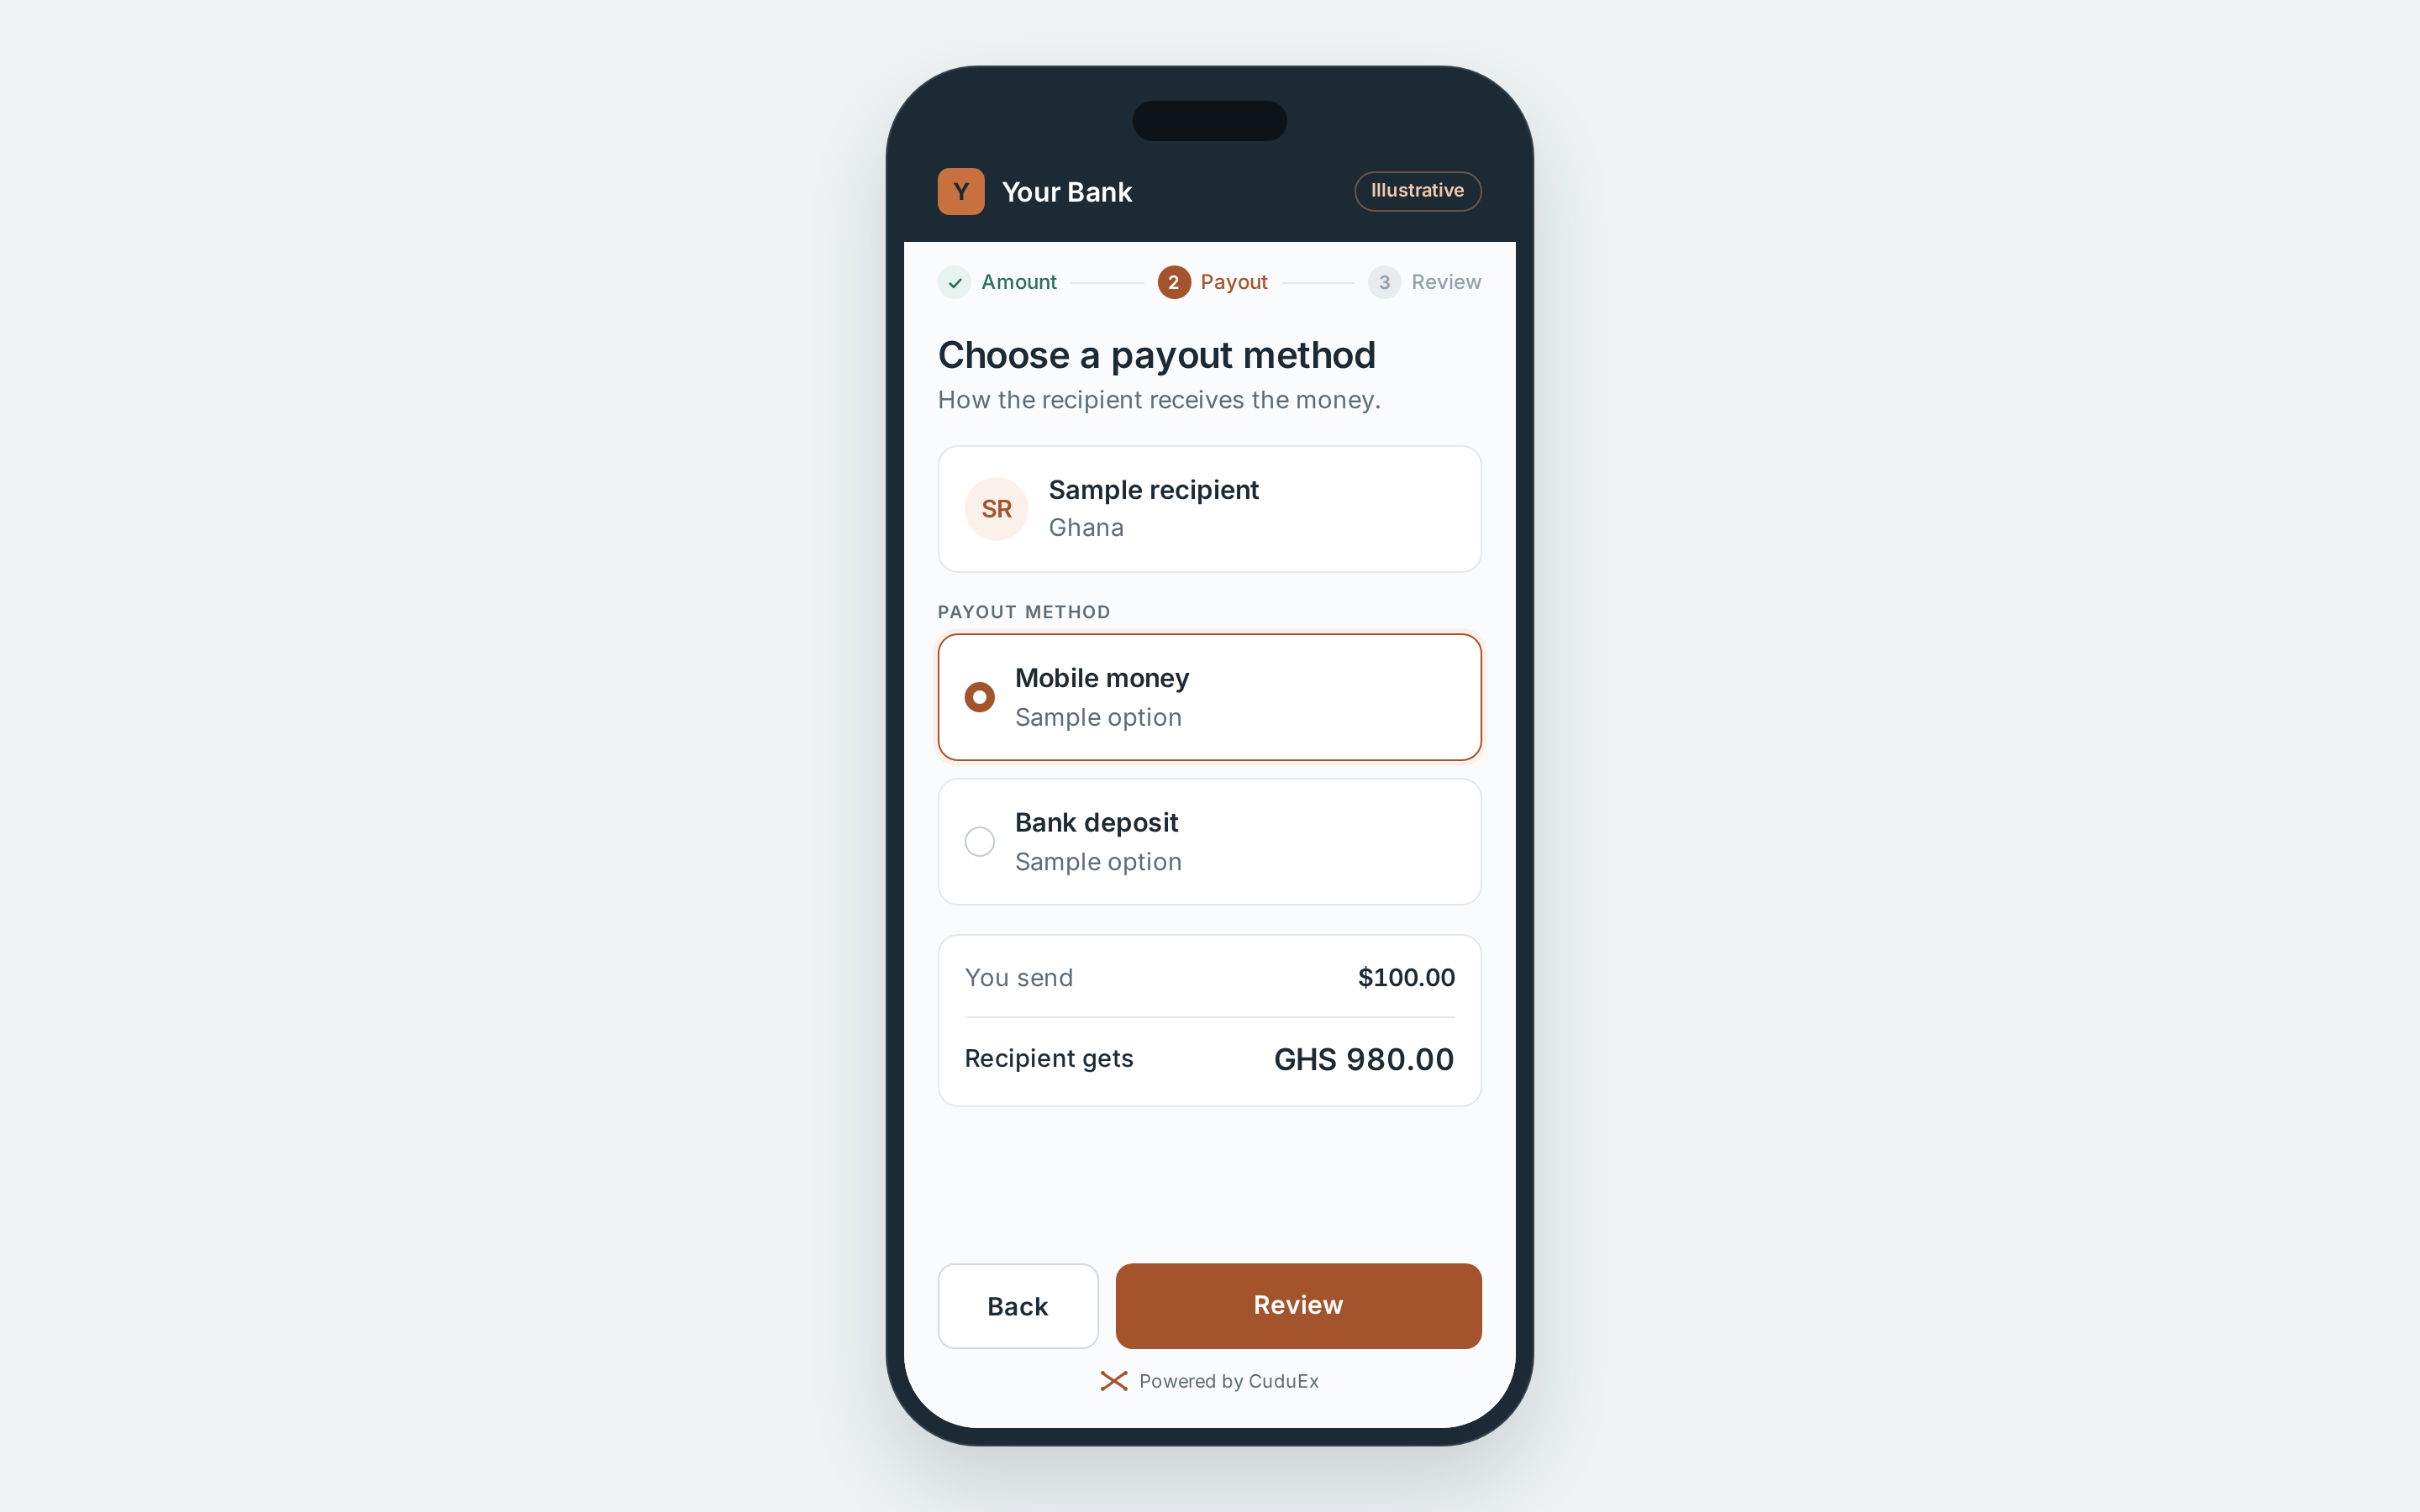
Payout.
The sender would choose how the recipient is paid, by mobile money or bank deposit.
Illustrative design mockup. Fictional institutions and figures; not a live product.
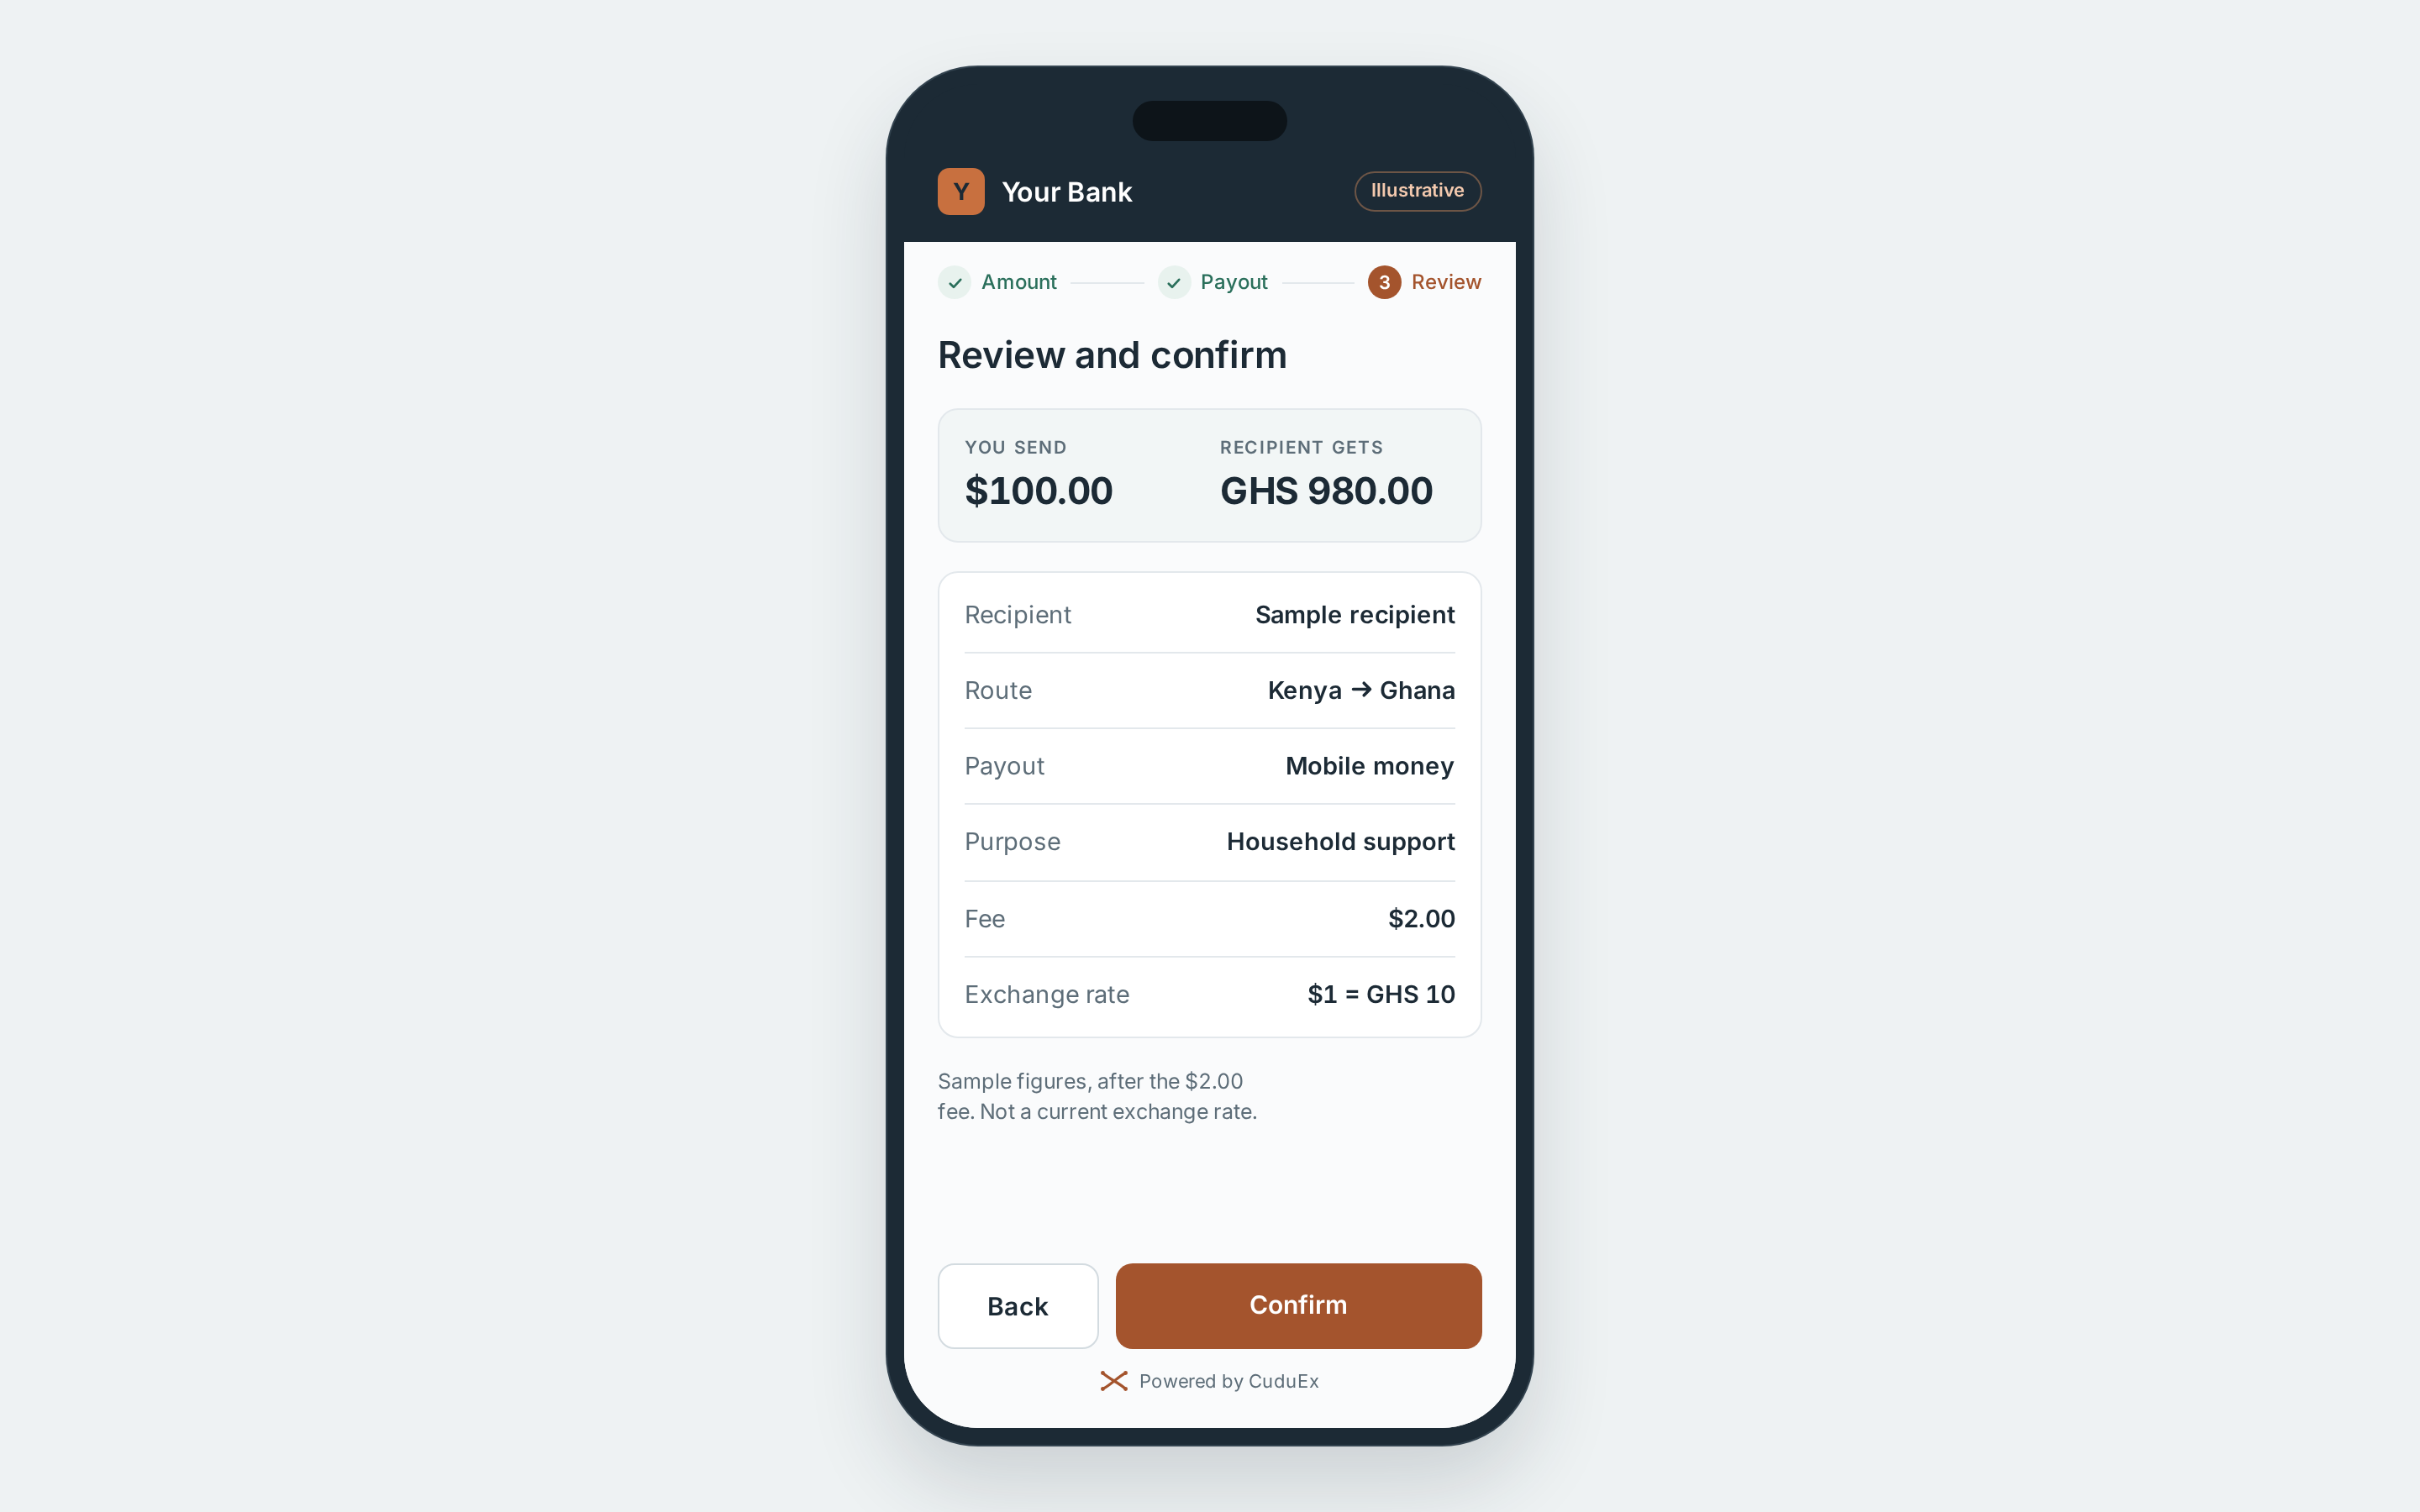
Review.
The sender would check the recipient, route, payout, purpose, fee and rate before confirming.
Illustrative design mockup. Fictional institutions and figures; not a live product.
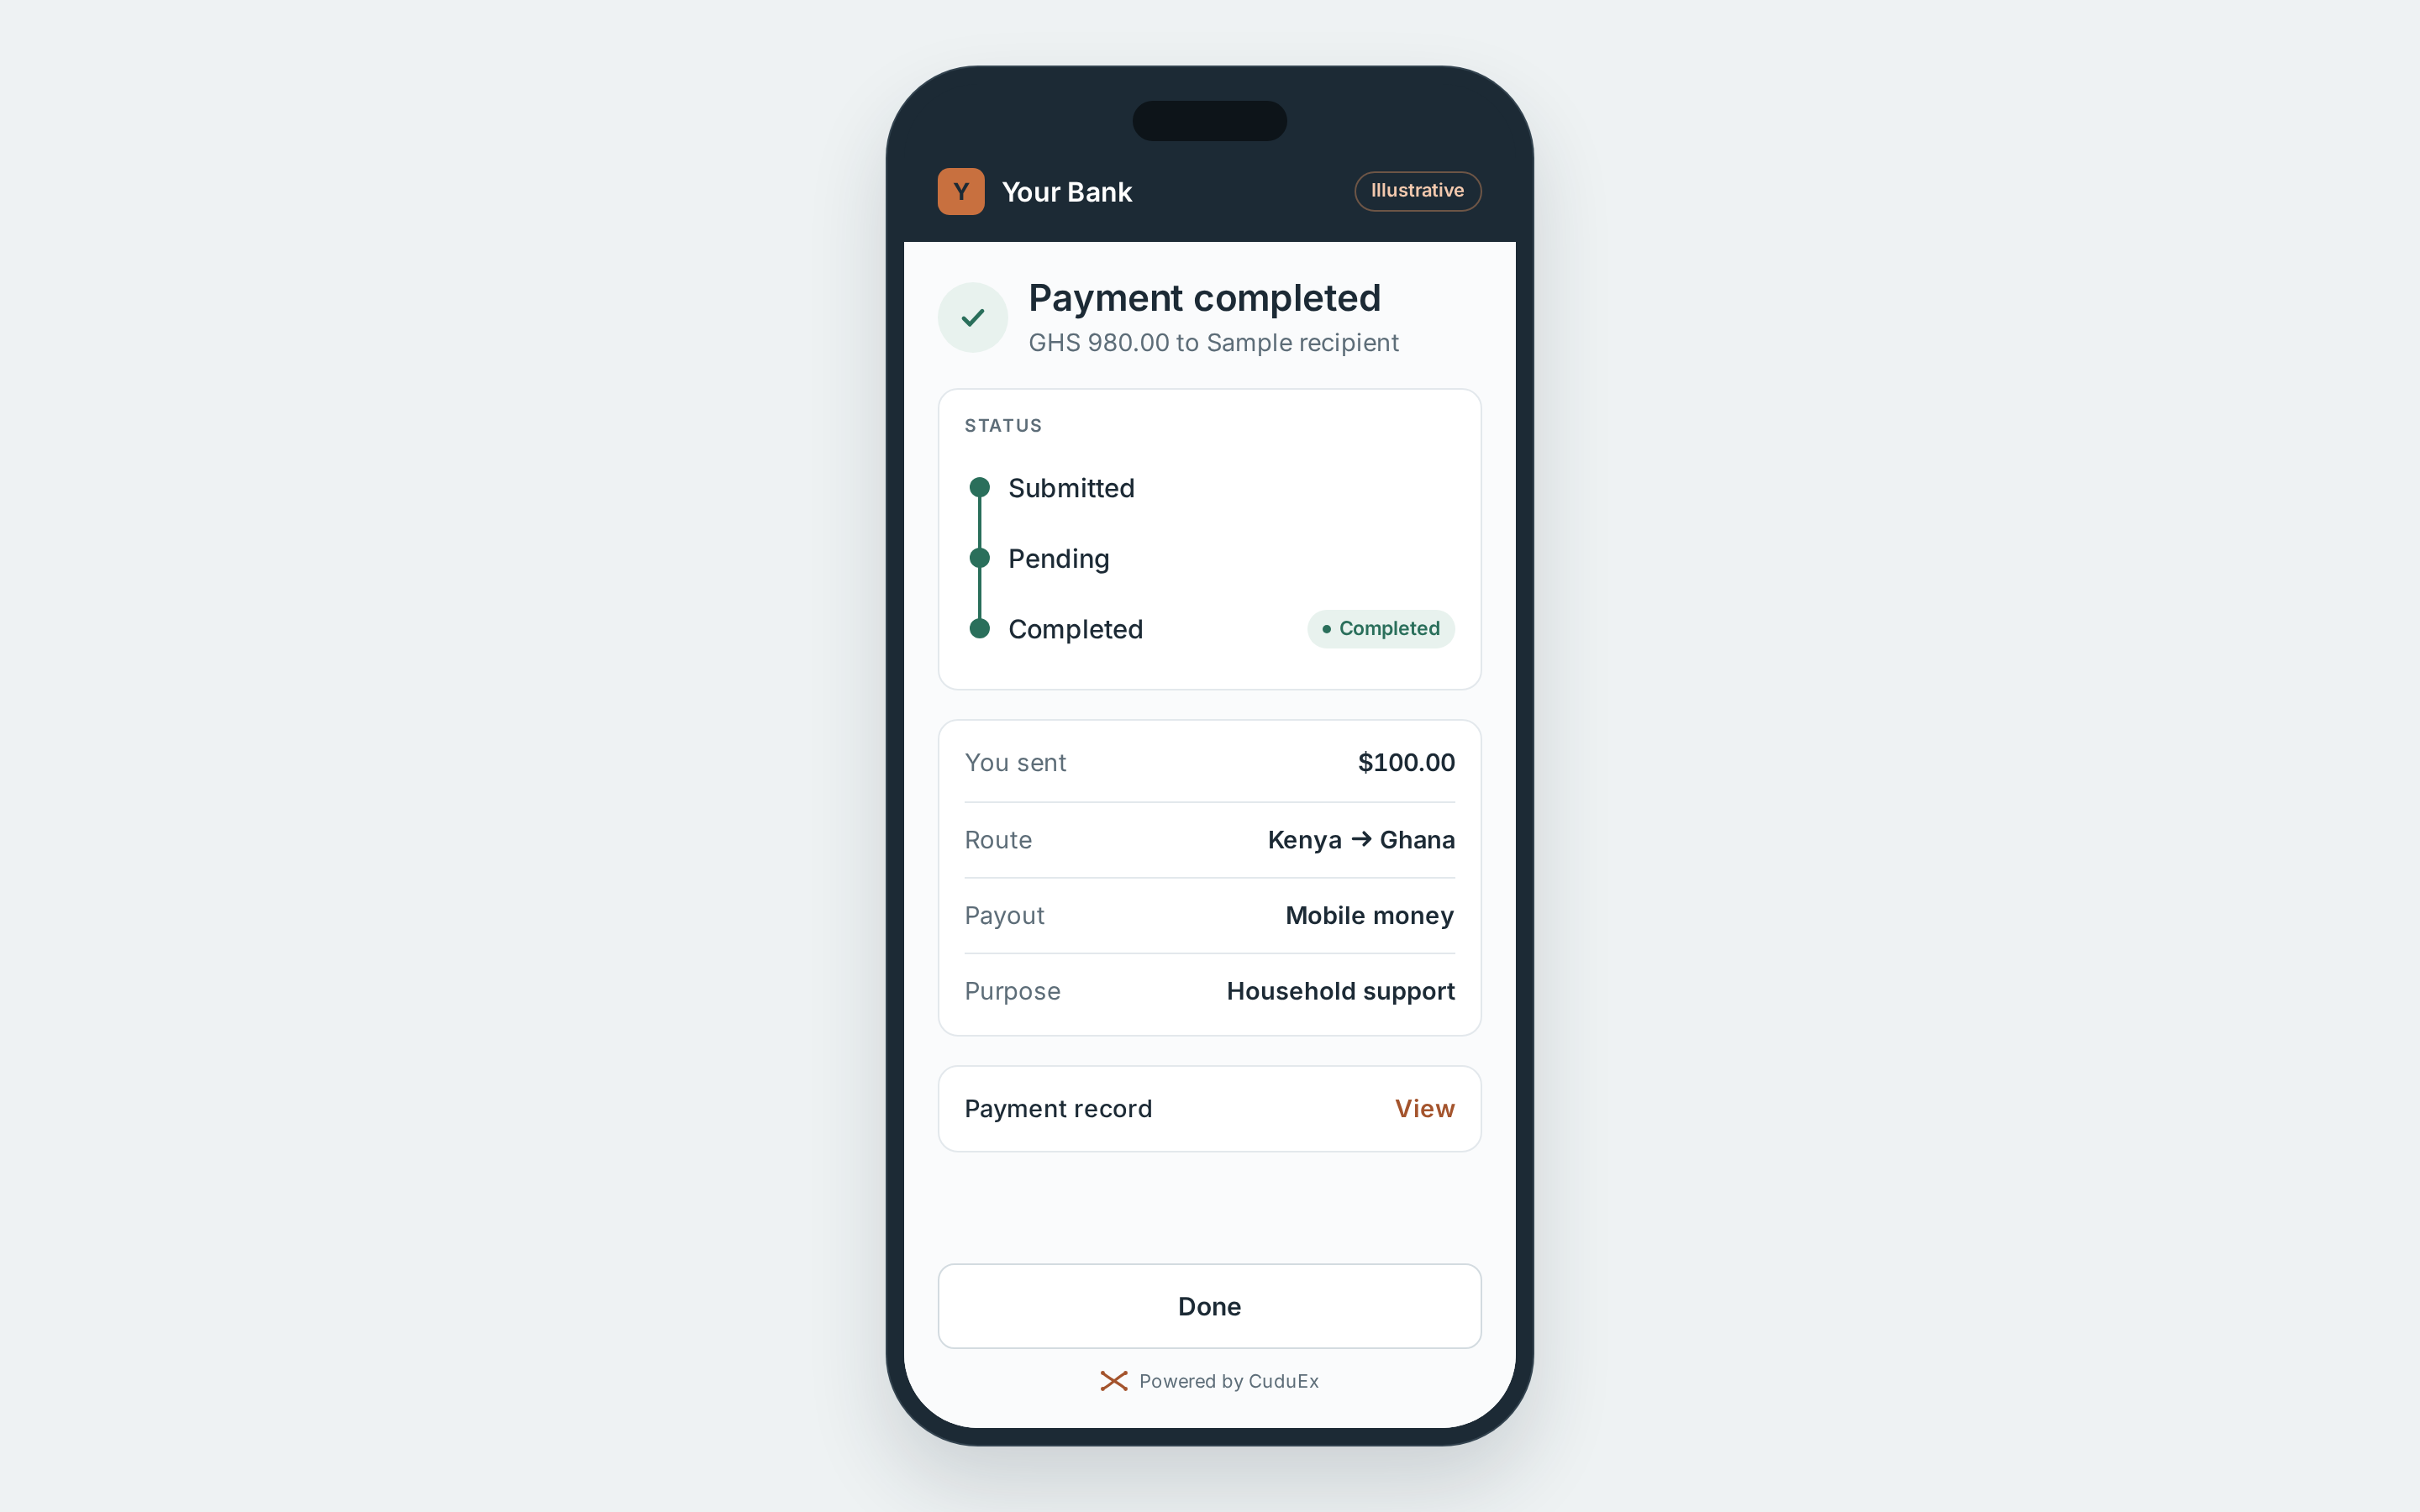
Status.
The sender would follow the payment from submitted to pending to completed, with a payment record.
Illustrative design mockup. Fictional institutions and figures; not a live product.
Institutional controls are not an add-on.
Transaction controls
Compliance and risk controls are designed into the settlement workflow.
Market-aware rollout
Product and corridor availability are shaped around applicable regulatory conditions.
Partner-led onboarding
The partner institution retains customer ownership and KYC responsibilities.
Transparent service rails
Custody, payment and brokerage steps operate as a coordinated institutional layer.
Access to stablecoins
Will let your customers move between local currency and stablecoins, and pay across borders, inside your own app, once authorised.
Settlement in minutes
Cross-border payments on stablecoin rails, with local currency at both ends - designed to settle in minutes, not days.
A new revenue line
Retained deposits plus a new fee line on the customers you already serve.
Single integration point
One REST API for stablecoin payments, custody, brokerage, tokenization and yield. Not five vendors, five contracts and five integrations.
White-labelled via a single API connection
Your name on the screen, your relationship, your KYC - our infrastructure behind it.
Built for compliance
Built so originator and beneficiary information travels with every transfer, with a full audit trail - designed to operate inside the framework you already run.
One API.
Full Infrastructure.
Designed for compliance from day one
Regulatory status
CuduEx Ltd is the group holding company and holds no client assets. Its subsidiaries will provide the group's financial services.
No company in the CuduEx Ltd group currently holds a licence to carry on virtual asset business in any jurisdiction. Havenex Botswana (Pty) Ltd is preparing an application to the Non-Bank Financial Institutions Regulatory Authority of Botswana for a licence under the Virtual Assets Act, 2025 (Act No. 4 of 2025). A further application is planned in Rwanda once the Capital Market Authority opens its licensing programme.
The services described on this website reflect the offering the group intends to provide once the necessary authorisations have been granted. No regulated service is provided before authorisation.
Our services are intended for licensed financial institutions and other professional and institutional counterparties only. They are not offered to retail customers.
Discuss a corridor, product scope
or partner model.
Tell us who you are and the CuduEx team will follow up with the appropriate institutional conversation.